Frozen Pipes Exclusion and the “Reasonable Care to Maintain Heat” Requirement (NY Law)

October 2026, by Aaron Jacob, Esq.

Every winter, pipes freeze and burst, causing some of the most expensive water damage claims that a property owner can face. A single ruptured pipe can flood multiple floors of a house within hours, and because pipes often burst while a property is empty, the damage may go undiscovered for days or weeks. This often happens in seasonal homes, or where an insured purchases a property in the winter but has not yet moved in.

Most homeowners and property policies cover water damage caused by frozen pipes. However, nearly all property policies contain a “freezing” exclusion that removes that coverage, usually while the property is vacant or unoccupied, unless the insured used “reasonable care” to maintain heat in the building, or to shut off the water supply and drain the system. After a freeze-related loss, insurers routinely invoke this exclusion, pointing to gas or electric bills, the thermostat setting, how often anyone checked on the property, or a utility shut-off notice, and argue that the insured did not do enough.

New York courts have enforced the exclusion where an owner took essentially no steps to keep a property heated. But they have also found coverage, or at least sent the question to a jury, where the owner took real, reasonable steps that turned out to be unsuccessful. The difference between those outcomes usually comes down to what the owner actually did before the pipes froze.

An analysis of how New York courts apply the “reasonable care to maintain heat” requirement is below, including what courts treat as reasonable care, how utility shutoffs are treated, the stricter “do your best” and minimum-temperature provisions found in some policies, and what to do before winter so that a frozen pipe claim is not denied on this basis.

What Is the Freezing Exclusion?

A typical homeowners or commercial property policy contains the following, or a similar, exclusion for damage caused by:

a. freezing of a plumbing, heating air conditioning or automatic fire protective sprinkler system or of a household appliance, or by discharge, leakage or overflow from within the system or appliance caused by freezing. This exclusion applies only while the dwelling is vacant, unoccupied or being constructed unless you have used reasonable care to:
(1) maintain heat in the building; or
(2) shut off the water supply and drain the system and appliances of water.1

The exact wording of the exclusion can vary from policy to policy, and some policies include the requirement to maintain heat as a policy “condition” rather than, or in addition to, the exception to the freeze exclusion.2 Regardless, an insurer looking to deny coverage for damage caused by a frozen pipe under this type of provision generally asks the following questions: (1) whether the loss was actually caused by freezing; (2) if the policy so limits the exclusion, whether the property was “vacant” or “unoccupied” at the time; and (3) whether the insured used reasonable care to maintain heat, or to shut off the water and drain the system.

Generally, under New York law, an insurer bears the burden of establishing that an exclusion to coverage applies, while an insured bears the burden of establishing that an exception to an exclusion applies.3 However, when applying the freeze exclusion and the exception to the freeze exclusion (reasonable care to maintain heat), New York appellate courts have placed the entire burden on the insurer and required the insurer to show that the insured failed to use reasonable care.4 At least one court, however, has placed the burden on the insured where the heat requirement was treated as a true exception.5 Either way, the practical lesson is the same: an insured who can document the steps taken to keep the property heated is in a far stronger position.

Notably, policies often limit the freeze exclusion to a “vacant” or “unoccupied” property, and so the exclusion would not apply at all to a home that was occupied (whether by the insureds or by other people). Courts have explained that “[i]t is the regular presence of inhabitants that makes occupancy,”6 and that a person’s presence in a house “for sleeping and eating and working purposes can literally constitute occupancy.”7 While the broader question of whether a home is occupied under different circumstances is outside the scope of this article, a seasonal home left empty for the winter will generally be considered “unoccupied.”8

I. What Counts as “Reasonable Care” to Maintain Heat?

“Reasonable care” is generally measured by what an ordinarily prudent person would do under the same or similar circumstances.9 The Fourth Department has gone further, holding that the phrase is ambiguous and must therefore be construed in favor of the insured, while the Third Department has disagreed.10 Either way, the standard is objective, and the question is whether the insured’s actions were reasonable under the circumstances, not whether the insured personally believed that he or she did enough.11 This determination is generally fact-specific.

Importantly, the requirement is to use reasonable care, not to guarantee that the pipes will never freeze. As such, the reasonable care standard can be satisfied in any number of situations in which a property owner took substantial steps to maintain heat but nonetheless failed to prevent frozen pipes through no fault of their own.12

Moreover, the exclusion does not apply in every case where a loss is caused by a lack of heat.13 As the Fourth Department explained, there is no “per se rule that a policyholder’s failure to conduct regular interior inspections at specific intervals, irrespective of any other efforts, constitutes a failure to use ‘reasonable care’ to maintain heat.”14 Similarly, where an insurer argued that the owner should have reviewed the gas bills, visited during the specific cold snap, and had a cold-weather protocol in place, the court explained that if the insurer wished to require those measures, “the policy form could have done so.”15

The Spectrum: From “No Steps” to “Reasonable, Albeit Unsuccessful, Efforts”

The cases fall along a spectrum. At one end are owners who took essentially no steps to keep a property heated, and courts have denied coverage as a matter of law. In one First Department case, the owner never purchased heating oil or contracted with an oil supplier in the 18 months it owned the building, and never told its caretaker that the building was heated with oil, how to check the oil level, or where the tank was.16 Similarly, the Third Department denied coverage where a home was left unoccupied from December to March with no arrangement for anyone to check the interior, and the gas consumption was too low to have prevented freezing.17

At the other end are owners who took real, documented steps to maintain heat, and courts have rewarded those efforts by finding coverage as a matter of law. For example, in McAleavey, the owner of a seasonal home kept the heat at about 50 degrees, had a newly installed and regularly maintained heating system, and visited roughly fifteen times over the winter to check the temperature, windows, and fixtures, until he was hospitalized with a broken leg, after which neighbors and a realtor checked the outside of the house.18 The Fourth Department distinguished those “reasonable—albeit unsuccessful—efforts” from cases of neglect and granted the insured summary judgment.19 As another example, in Gallo, the insured also won as a matter of law where the property manager restored electricity to a vacant rental and confirmed the furnace was operating two days before the freeze.20

Most cases fall somewhere in between, and in those cases courts generally find that whether the insured used reasonable care is a question of fact for a jury.21

The Factors Courts Look At

In practice, the factors that courts22 (and insurers) most often focus on include:

• the thermostat setting, with settings of about 50 to 55 degrees commonly at issue;

• whether there was a reliable fuel supply, such as an automatic oil delivery arrangement;

• whether the heating system was serviced and in good working order;

• how often someone checked the inside of the property, and whether that person actually checked the heat;

• whether any caretaker, property manager, or realtor was clearly instructed on what to check and how;

• the gas or electric usage during the cold period; and

• how the owner responded to warning signs, such as falling temperatures, a heating problem, or a utility shut-off notice.

Insurers frequently rely on utility records to argue that the heat was off. For example, insurers have retained engineers to compare gas consumption against outdoor temperatures and conclude that too little fuel was used to keep the property above freezing.23 Those records are not always the end of the analysis. In Gallo, utility records showing “no record of electric service” did not raise an issue of fact where witnesses confirmed that the electricity was on and the furnace was running shortly before the freeze.24

Insureds should also be aware that the conduct of a property manager or other agent may be charged to the owner. In ADAR, the property manager’s log showed declining temperatures, including 41 degrees days before the loss, with no response, and the court held that the manager’s failures were attributable to the owner.25 An arrangement with a realtor or friend to check on a property can also become a point of dispute where it was informal and unconfirmed.26

Utility Shutoffs

Utility shutoffs are a recurring source of frozen pipe denials, particularly for rental properties between tenants. Courts have denied coverage as a matter of law where an owner ignored repeated “final turn-off” notices,27 and where a landlord learned that the power had been cut in the middle of winter but declined to return to the property so the utility could restore service. In the latter case, the court held that the owner “knew or should have known that he should return to the Property without delay,” and described his failure to act as “the equivalent of ignoring the obvious and burying one’s head in the sand.”28

By contrast, an owner who promptly asks the utility to restore service and reasonably relies on its assurances may raise a question of fact. In Billitier, the owner discovered that the power had been shut off after his tenants left, immediately called the utility, and was told that power would be restored within days. The utility’s attempt to restore power failed, and it never told him. The court held that whether the owner used reasonable care, including whether he should have drained the pipes or provided another source of heat in the meantime, was a question for the jury.29

Examples of how New York courts have applied these principles include:

(1) No coverage, where the owner never purchased heating oil or contracted with an oil supplier, and never instructed its caretaker on how to maintain the heat.30

(2) No coverage, where the home was unoccupied from December to March with no arrangement for anyone to check the interior, and gas usage was too low to prevent freezing.31

(3) No coverage, where the owner ignored repeated final shut-off notices and the utility cut off gas and electric service.32

(4) No coverage, where the landlord learned the power had been cut in mid-winter and declined to return to the property to allow the utility to restore service.33

(5) Question of fact, where an automatic fuel oil delivery arrangement may have remained in effect.34

(6) Question of fact, where the thermostat was left at 55 degrees and the insured and her mother visited periodically.35

(7) Question of fact, where the owner promptly asked the utility to restore power and relied on its assurances, but the utility’s attempt failed and it never told him.36

(8) Question of fact, where the owner was abroad for five weeks with the thermostats at about 55 degrees, and the parties disputed whether a realtor had agreed to check on the house.37

(9) Question of fact, where the owner and a property manager regularly inspected the building, but gas bills showed no heat in one unit for three months.38

(10) Coverage, where the property manager restored power to the building and the furnace was confirmed operating two days before the freeze.39

(11) Coverage, where the owner kept the heat at about 50 degrees, maintained the heating system, and checked the home roughly fifteen times over the winter before being hospitalized.40

Key takeaway: Reasonable care is about what you did, not whether the pipes froze. Keep the heat at a sensible level, keep the fuel supply and heating system in working order, have someone actually check the inside of the property and the thermostat on a regular schedule, give that person clear instructions, and respond immediately to any warning sign, especially a utility shut-off notice. Then document all of it.

II. When the Policy Requires More: “Do Your Best” or Minimum-Temperature Provisions

Not every policy uses the “reasonable care” standard. Some commercial and other policies require the insured to “do your best to maintain heat in the building or structure.” The First Department has held that phrase unambiguous, and denied coverage where the owner took essentially no steps to maintain heat.41 At least one court has noted that “best efforts” may impose a higher standard than reasonable care, although it left that question open.42

Other policies go further, and contain an endorsement requiring that heat be maintained at a specific minimum temperature. Courts have generally enforced these provisions as written. For example, the First Department denied coverage under a “Heat Condition” endorsement requiring heat “at a minimum of 55 degrees Fahrenheit,” where the building’s rooftop heating units were turned off and the insurer’s experts showed, based on electrical consumption, that the baseboard heaters alone could not have maintained 55 degrees.43 Similarly, a federal court enforced an endorsement requiring an ambient temperature of at least 50 degrees “at all times” as an absolute condition, holding that the owner’s reasonable efforts did not matter once the temperature fell below that level.44

Key takeaway: Read the entire policy, including every endorsement, before winter. If your policy contains a minimum-temperature requirement, the question is no longer whether you were reasonable, but whether the building stayed above the stated temperature, which may call for a temperature monitoring device or a different coverage arrangement.

III. Was the Loss Actually Caused by Freezing?

Finally, the exclusion applies only if the loss was caused by freezing, and that is not always clear. For example, in Farrell, the insured’s experts opined that the burst pipe ran along an interior wall, that no pipes along exterior walls had frozen, and that an unrelated leak had flooded the basement and shut down the boiler, so that the lack of heat was the result of the water damage, not its cause.45 Similarly, the timing of a heating system failure (before or after the pipes burst) can be a key factual dispute.46

The exact wording of the exclusion also matters. The Court of Appeals held that an exclusion for loss “caused by … freezing” did not bar coverage for water damage from a frozen and ruptured sprinkler head, because the loss was caused by the water damage, not the freezing itself.47 Many modern policies now expressly exclude “discharge, leakage or overflow” caused by freezing, but narrower wording should be read carefully.

If your frozen pipe claim is denied, confirm:

• The exact wording of the freezing exclusion or condition, including whether it applies only while the property is vacant or unoccupied, and any “do your best” or minimum-temperature endorsement;

• Whether the property was in fact occupied at the time of the loss;

• What you (and any property manager, caretaker, or family member) did to maintain heat: the thermostat setting, fuel deliveries, service records for the heating system, and the dates of each visit to the inside of the property;

• The utility records the insurer relies on, and whether any expert analysis of those records accounts for the actual conditions at the property; and

• Whether the loss was actually caused by freezing, or whether a separate failure (such as an unrelated leak or a mechanical failure) caused the heat to stop.

Before winter, or before leaving a property vacant or unoccupied, build these protections into your routine:

• Keep the heat on at a sensible temperature (and at or above any minimum stated in your policy), and confirm the fuel supply, such as an automatic oil delivery contract, is in place;

• Have the heating system serviced before the cold season;

• Arrange for someone to check the inside of the property and the thermostat on a regular schedule, give them written instructions, and keep a log of each visit;

• Consider a remote temperature monitor or alarm, and watch your gas and electric bills for unusually low usage;

• Respond immediately to any utility shut-off notice or loss of service, and if heat cannot be restored promptly, shut off the water supply and drain the system; and

• For a property that will be empty for an extended period, consider shutting off the water and draining the system, and notify your broker to confirm the property remains properly insured.

* * *

Aboulafia Law Firm LLC works exclusively on behalf of policyholders and has decades of experience fighting insurance companies. Whether you are dealing with a residential or commercial property claim, we are ready to help you. If your insurer has denied your frozen pipe or water damage claim, don’t navigate the complex claims process alone. For assistance on your insurance claim, please contact us.

The opinions expressed are those of the author(s) and do not necessarily reflect the views of the firm, its clients, or any of its or their respective affiliates. This article is for general information purposes and is not intended to be and should not be taken as legal advice.


Footnotes

1. Billitier v. Merrimack Mut. Fire Ins. Co., 777 F. Supp. 2d 488, 490–92 (W.D.N.Y. 2011) (quoting policy) (emphasis added); see also Stephenson v. Allstate Indem. Co., 160 A.D.3d 1274, 1275–76 (3d Dept. 2018); McCabe v. Allstate Ins. Co., 260 A.D.2d 850, 852 (3d Dept. 1999). ↩

2. Farrell v. Am. Int’l Ins. Co., 2010 N.Y. Slip Op. 31501(U), at *7–8 (Sup. Ct. Nassau Cnty. May 31, 2010); ADAR 1165 LLC v. U.S. Liab. Ins. Co., No. 23-cv-6437 (JSR), 2024 WL 1513708, at *2 n.1 (S.D.N.Y. Apr. 8, 2024) (policy contained the requirement to maintain heat both as an exception to the freeze exclusion and as a policy condition). ↩

3. Platek v. Town of Hamburg, 24 N.Y.3d 688, 694 (2015); Corbel Constr. Co. v. Arch Specialty Ins. Co., 160 A.D.3d 703, 704 (2d Dept. 2018) (“where the existence of coverage depends entirely on the applicability of an exception to the exclusion, the insured has the duty of demonstrating that it has been satisfied”) (internal quotation marks and citations omitted). ↩

4. Stephenson, 160 A.D.3d at 1275–76 (exclusion “applies only when the insurer establishes that the insured failed to ‘use reasonable care’ to maintain the heat”); Place v. Preferred Mut. Ins. Co., 190 A.D.3d 1208, 1209–11 (3d Dept. 2021); Gallo v. Midstate Mut. Ins. Co., 45 A.D.3d 1492, 1493–94 (4th Dept. 2007); Dean v. Tower Ins. Co. of N.Y., 19 N.Y.3d 704, 708–09 (2012). ↩

5. ADAR, 2024 WL 1513708, at *3 & n.6 (placing the burden on the insured, who conceded that the provision was an “exception to the exclusion”). ↩

6. McCabe, 260 A.D.2d at 852 (internal quotation marks and citation omitted). ↩

7. Dean, 19 N.Y.3d at 708–09 (quoting Page v. Nationwide Mut. Fire Ins. Co., 15 A.D.2d 306, 307 (3d Dept. 1962)). ↩

8. McCabe, 260 A.D.2d at 852. ↩

9. Zimmerman v. Leatherstocking Coop. Ins. Co., 226 A.D.3d 1239, 1240–41, 210 N.Y.S.3d 316 (3d Dept. 2024). ↩

10. McAleavey v. Chautauqua Patrons Ins. Co., 195 A.D.3d 1551, 1552–53 (4th Dept. 2021) (ambiguous); Zimmerman, 226 A.D.3d at 1241 (unambiguous, declining to follow McAleavey). ↩

11. See ADAR, 2024 WL 1513708, at *3–7. ↩

12. Id. at *5. ↩

13. Stephenson, 160 A.D.3d at 1275–76. ↩

14. McAleavey, 195 A.D.3d at 1552–53. ↩

15. ADAR, 2024 WL 1513708, at *3–7. ↩

16. Nesher, LLC v. Realm Nat’l Ins. Co., 6 A.D.3d 242, 243 (1st Dept. 2004). ↩

17. Stephenson, 160 A.D.3d at 1275–76. ↩

18. McAleavey, 195 A.D.3d at 1552–53. ↩

19. Id. ↩

20. Gallo, 45 A.D.3d at 1493–94. ↩

21. See ADAR, 2024 WL 1513708, at *3–7; Place, 190 A.D.3d at 1209–11; Zimmerman, 226 A.D.3d at 1241–42; Farrell, 2010 N.Y. Slip Op. 31501(U), at *7–8. ↩

22. See McAleavey, 195 A.D.3d at 1552–53; McCabe, 260 A.D.2d at 852; Nesher, 6 A.D.3d at 243; ADAR, 2024 WL 1513708, at *3–7; Zimmerman, 226 A.D.3d at 1241–42; Stephenson, 160 A.D.3d at 1275–76. ↩

23. Stephenson, 160 A.D.3d at 1275–76; ADAR, 2024 WL 1513708, at *3–7; Farrell, 2010 N.Y. Slip Op. 31501(U), at *7–8. ↩

24. Gallo, 45 A.D.3d at 1493–94. ↩

25. ADAR, 2024 WL 1513708, at *3–7. ↩

26. Zimmerman, 226 A.D.3d at 1242. ↩

27. Brennor v. Metro. Prop. & Cas. Ins., 2014 N.Y. Slip Op. 32868(U) (Sup. Ct. Westchester Cnty. May 12, 2014), reargument denied, 2014 N.Y. Slip Op. 32861(U) (Sup. Ct. Westchester Cnty. Sept. 24, 2014). ↩

28. Landsman v. Dryden Mut. Ins. Co., 26 Misc. 3d 1211(A), 2009 N.Y. Slip Op. 52708(U), at *4–5 (Sup. Ct. Broome Cnty. 2009). ↩

29. Billitier, 777 F. Supp. 2d at 490–92. ↩

30. Nesher, 6 A.D.3d at 243. ↩

31. Stephenson, 160 A.D.3d at 1275–76. ↩

32. Brennor, 2014 N.Y. Slip Op. 32868(U). ↩

33. Landsman, 2009 N.Y. Slip Op. 52708(U), at *4–5. ↩

34. McCabe, 260 A.D.2d at 852. ↩

35. Place, 190 A.D.3d at 1209–11. ↩

36. Billitier, 777 F. Supp. 2d at 490–92. ↩

37. Zimmerman, 226 A.D.3d at 1242. ↩

38. ADAR, 2024 WL 1513708, at *3–7. ↩

39. Gallo, 45 A.D.3d at 1493–94. ↩

40. McAleavey, 195 A.D.3d at 1552–53. ↩

41. Nesher, 6 A.D.3d at 243. ↩

42. ADAR, 2024 WL 1513708, at *5 n.8 (citing Garner’s Dictionary of Legal Usage). ↩

43. Convention Plaza III, LLC v. Seneca Specialty Ins. Co., 147 A.D.3d 692, 693 (1st Dept. 2017). ↩

44. Read Prop. Grp. LLC v. Hamilton Ins. Co., No. 16 CV 4573 (CLP), 2018 WL 1582291, at *9–11 (E.D.N.Y. Mar. 30, 2018). ↩

45. Farrell, 2010 N.Y. Slip Op. 31501(U), at *7–8 (denying the insurer’s motion for summary judgment). ↩

46. See Zimmerman, 226 A.D.3d at 1242 n.2; Place, 190 A.D.3d at 1209–11. ↩

47. Album Realty Corp. v. Am. Home Assur. Co., 80 N.Y.2d 1008 (1992). ↩
“Two-Family” or “Three-Family”? How New York Courts Count “Units” in Material Misrepresentation Disputes (NY Law)

October 2026, by Aaron Jacob, Esq.

An application for a homeowners insurance policy in New York typically asks how many “families” or “units” the building contains, and the answer determines whether the insurer will write the policy, how much the premiums will cost, and which forms the policy will contain. For the owner of a two-family house, that single answer, “2,” can become the most scrutinized statement in the entire claims file.

This issue usually surfaces after a fire or other large loss. If an adjuster or investigator hired by your insurer inspects the house and finds, for example, a finished basement or a livable attic room, the insurer can take the position that the house was really a “three-family” dwelling and try to rescind the policy ab initio (i.e., from its inception), because there was a “material misrepresentation” in the policy application. This can happen even where the insured’s answer was based upon the official deed of the house identifying the property as a “one to two-family house”, and even after years of premiums were paid on the same policy.

However, while some third units may truly make a dwelling a “three-family house”, New York courts have refused to rescind policies or deny coverage where the supposed “third unit” did not truly transform the otherwise two-family house into a three-family house, such as where the “third unit” was part of a family’s own living space, or where the third unit did not contain the necessary living appliances to be deemed an independent living space.

An analysis of how New York courts decide these disputes is below, including how courts determine whether a space is a separate “unit,” how the wording of the application question can affect whether there was a misrepresentation at all, and what to confirm at the application stage so that a future claim does not turn on this question.

What Is a Material Misrepresentation?

An insurance application is made up of representations, or statements of fact submitted by the applicant to persuade the insurer to issue the policy. A mistake in these representations can be considered a “misrepresentation.”1 However, not all misrepresentations are equal. Under New York Insurance Law § 3105, a misrepresentation does not void a policy unless it is “material”, and “[n]o misrepresentation shall be deemed material unless knowledge by the insurer of the facts misrepresented would have led to a refusal by the insurer to make such contract.”2

If an insurer discovers a misrepresentation, it has several options. It can ignore the misrepresentation and continue insuring the property, it can choose to cancel the policy going forward, or it can try to rescind the policy, ab initio, meaning the policy is treated as void from its inception, as if it was never issued.3 After a loss occurs, cancelling the policy going forward will not help the insurer avoid the claim, so insurers must pursue the third option, rescission4, but to do so, an insurer will have to prove that the misrepresentation was “material.”

Critically, under New York law, and as often stressed by insurers, even an innocent misrepresentation can support rescission if that misrepresentation is “material”.5 That rule makes the remaining elements of the insurer’s burden all the more important.

A common misrepresentation that insurers argue is material is where an application states that a house is a “two-family”, but the insurer claims that the house is really a “three-family”. When an insurer rescinds a policy based on this misrepresentation, it generally must establish:

(1) that the application contained a misrepresentation, i.e., that the building actually contained more dwelling units than the application represented;
(2) that the misrepresentation was material, i.e., that the insurer would not have issued the same policy (or at the same premium) had it known the true facts; and
(3) that the insurer has not waived, and is not estopped from asserting, its right to rescind.

This article focuses on the first element: whether there was a misrepresentation at all, i.e., whether the house actually contained a third unit.

Of note, the same number-of-units question can also arise outside of rescission, specifically, in the “residence premises” policy provision. This is because many homeowners policies state that coverage is limited to the “residence premises”, which is usually defined as a one- or two-family dwelling where the insured resides.6 So, insurers may argue that a loss to a house with an undisclosed third unit falls outside of coverage because the property was not a “residence premises.”7 The analysis discussed below concerning how many units a property contains applies equally to a misrepresentation defense and a “residence premises” defense.

Was There a Misrepresentation? Counting the “Units” or “Families”

The First Department has explained that the term “family,” as used in the phrases “one family dwelling” or “two family dwelling,” refers to an entire self-contained dwelling unit, and not the number of people or households living in the building.8 As a result, a house with three self-contained apartments has been treated as a three-family dwelling even where the insureds claimed that all of the residents lived together as a single household,9 and a house with two self-contained units remains a two-family house even if multiple families live in one of the units.10

As the Southern District of New York explained, “a building with two separate units is no less a two-family dwelling if members of more than one family reside in one of the units than a building with three separate units becomes a two-family unit because of the happenstance that persons related to one another are spread over two of the units.”11 By the same logic, a house with three self-contained units is a three-family dwelling even if only one person lives there.

By the same token, an insurer’s mere characterization of a space as a “third dwelling unit” or an “illegal apartment” is not proof that it is a separate unit. For example, in Gottlieb v. Mountain Valley Indemnity Co., a 2026 decision, the First Department rejected a field investigator’s affidavit that called a basement “an illegal apartment” where he failed to explain how he reached that conclusion or state his qualifications to make it.12

Relatedly, the legal status of the property does not control the analysis in either direction. An insurer does not need to show that a third apartment was legal, as a building with three apartments has been found to be a three-family dwelling even though its certificate of occupancy and the City’s tax records described it as a legal two-family house.13 As such, a misrepresentation may still occur even if the insured represents the property on the application as it is described on a deed or New York city department documents.14

This is because, under New York law, determining the number of units within a property requires two considerations: (1) the “structural configuration” of the property; and (2) the “actual use” of the unit in question.15

The Structural Configuration Test

As stated, under New York law, “determining the number of units within a property requires consideration of its ‘structural configuration.’”16 This test takes into account whether each respective portion or area of the property has its own (i) kitchen, (ii) bathroom, and (iii) separate entrance.17 The second factor of this test is usually self-evident; however, the first and third factors are generally fact specific.

In this regard, courts look to whether the claimed unit has its own entryway that is not shared with, or reached only through, another unit.18 That entryway may be an exterior door or an interior door off a common hallway.19 A lock is not strictly required (at least one court found an interior door sufficient regardless of whether it could be locked),20 but a door with its own lock or key that cuts the space off from the rest of the house is strong evidence of a separate unit.21 Stated another way, the more freely the space can be reached from the other units, the weaker the insurer’s “separate entrance” argument.22

So, for example, a house with three exterior entrances leading to their respective floors would likely be considered “separate entrances.”23 As another example, a house with an immediate interior hallway with three individual doors that lead to the first floor, second floor, and basement, respectively, and the three floors are inaccessible from the others, would also likely be considered three separate entrances24, and the case is stronger still if each door has its own lock. Conversely, a house with just an interior staircase between the first floor and a basement, and the staircase cannot be accessed without use of the first-floor unit, may not be considered a separate entrance.25

The “kitchen” question deserves particular attention. To this end, in each of the leading appellate decisions where a “third unit” was found, the court described a separate kitchen.26 On this issue, insurers have prevailed in showing that an extra unit existed where the disputed area contained actual cooking facilities, such as a functioning range/oven, even when the insured described it as a mere “kitchenette.”27 Courts, however, have not treated the Housing Maintenance Code as controlling, and a space may still be found to be a separate unit based on its overall configuration.28

“Actual Use” or “Unifying Features”: When the Space Is Part of an Existing Unit

In addition to the required consideration of the structural configuration of a property, whether a dwelling is a two-family or three-family “is determined by actual use” of the property.29

For example, in Gottlieb, the insureds lived in one unit of a two-family house and their son’s family lived in the other, while the insurer claimed that the basement was a third independent unit.30 The First Department rejected the insurer’s position and affirmed the denial of its motion for summary judgment because, as the Court wrote: “‘unifying features’ exist which could suggest that the basement was merely a space used by plaintiffs and their son’s family, rather than a separate unit unto itself.”31 In this regard, the insurer’s own submissions indicated that the basement shared the same entrance as the other two units, and suggested that stairs led directly from the basement to one of the units. The Court also credited the insureds’ evidence that the basement was used to accommodate extended family and visitors, and that its kitchen was consistent with the practice of their community to facilitate dietary laws observed during Passover.32 As seen, even though the basement had some features of a separate unit (e.g., a kitchen), the actual use of the property showed that the basement was merely a space used by the families living in the upstairs portions of the house.

Similarly, in Walker v. Tighe, the Second Department held that, given the structural configuration of the insured’s property, the insurer failed to establish as a matter of law that the house was not a covered dwelling under the policy.33 It is the insurer’s burden to establish that there was a misrepresentation in the first place.

In practice, the facts that most often tie a disputed space to an existing unit include: (1) the absence of a stove, oven, or other cooking facilities; (2) the absence of a separate entrance, or access only through another unit or a shared entrance; (3) interior stairs or doors connecting the space to the rest of the house, particularly doors the rest of the household can freely pass through; (4) shared utilities and meters; (5) use of the space by the owner’s family, such as for storage, laundry, or a bathroom; and (6) occupancy by family members or occasional guests rather than a rent-paying tenant. These facts track the New York City Housing Maintenance Code, which defines an “apartment” as rooms arranged to be occupied as a unit separate from all other rooms in the dwelling, with lawful sanitary facilities and a lawful kitchen or kitchenette “for the exclusive use of the family residing in such unit.”34

Examples of how New York courts have applied these principles include:

(1) No coverage, where the premises contained three separate units, each with its own kitchen, bathroom, and separate entrance, even though the insureds claimed that all of the residents lived together as one household.35

(2) No coverage, where the insurer’s photographs and field adjuster’s affidavit showed three separate dwelling units, each with its own kitchen, bathroom, and separate entrance, and its underwriting rules showed it would not have issued the same policy for a three-family dwelling.36

(3) No coverage, where the building contained a third apartment, even though the certificate of occupancy and tax assessment records described it as a legal two-family house.37

(4) No coverage, where the insured admitted to the insurer’s investigator that the home was a three-family dwelling, and failed to explain why the premises had separate entrances.38

(5) No coverage, where the house had been divided into eleven numbered, deadbolted single rooms rented to unrelated occupants, the City issued violations for the illegal conversion, and the owners reported the property as rental income property on their tax returns.39

(6) Question of fact, where the basement contained a kitchen, but shared the same entrance as the other units, connected by stairs directly to one of the units, and was used to accommodate extended family members and visitors.40

(7) Question of fact, where, given the structural configuration of the property, the insurer failed to establish as a matter of law that the house was not a covered one-to-four-family dwelling.41

Key takeaway: If an insurer claims your house has a third unit, focus on the facts that tie the disputed space to an existing unit: no stove or oven, no separate entrance, interior access to the rest of the house, shared utilities, and use by family members or guests rather than a tenant. Document those facts with your own photographs before repairs or demolition begin, because the insurer’s adjuster will already be building the opposite record.

The Application Question: “Families,” “Units,” and Ambiguity

Whether an answer on an application was a misrepresentation also depends on how the question was actually asked. Under New York law, “[a]n answer to an ambiguous question on an application for insurance cannot be the basis of a claim of misrepresentation” where a reasonable person in the insured’s position could rationally have interpreted the question as the insured did.42 Applying that rule, federal courts held that an application asking for the number of “apartment units,” an undefined term, was ambiguous, and that a reasonable applicant could have understood it to exclude a furnished basement in which no one was residing and did not contain the necessary certificate to have someone living in it.43 The First Department has since relied on that reasoning to deny an insurer’s motion for summary judgment on the same “apartment units” question, where the application asked for the number of “apartment units”, but the related underwriting guidelines referred to “living units,” not apartment units.44

Policyholders should be aware, however, that the First Department has held that the question of “# Families” on a standard homeowners application is not ambiguous, and that it seeks the number of separate dwelling units in the building.45 The strength of an ambiguity argument therefore depends on the exact wording of the application, any instructions that accompanied it, and whether the insurer’s own documents define the term it is relying on.

Key takeaway: Obtain a copy of the actual application, and any instructions, that the insurer claims was misrepresented. The precise question asked (e.g., “families” versus “apartment units”) can matter as much as the layout of the house, and an undefined term in the insurer’s own form is construed against the insurer.

When applying for or renewing a homeowners policy, build these protections into the process before a loss occurs:

• Before applying, walk through the house with the structural test in mind, and identify any space (e.g., a basement, attic, or rear room) that has its own kitchen, bathroom, or separate entrance;

• Accurately describe every space that could be viewed as a separate unit, and ask your broker, in writing, how the insurer counts “families” or “units” on its application;

• Confirm that the declarations page reflects the correct number of families at every renewal;

• If you add a kitchen, bathroom, or separate entrance, or otherwise convert space in the house, notify your broker in writing and confirm the policy is updated; and

• Keep copies of the application, every renewal declarations page, your communications with your broker, and photographs of the layout of the house.

* * *

Aboulafia Law Firm LLC works exclusively on behalf of policyholders and has decades of experience fighting insurance companies. Whether you are dealing with a residential or commercial property claim, we are ready to help you. If your insurer has rescinded your homeowners policy or denied your claim based on the number of units in your home, don’t navigate the complex claims process alone. For assistance on your insurance claim, please contact us.

The opinions expressed are those of the author(s) and do not necessarily reflect the views of the firm, its clients, or any of its or their respective affiliates. This article is for general information purposes and is not intended to be and should not be taken as legal advice.

Aaron Jacob is a senior associate at Aboulafia Law Firm LLC. Mr. Jacob is a skilled litigation and coverage attorney and has extensive experience representing commercial and private clients involved in property damage and insurance coverage claims in complex state and federal court matters.

Mr. Jacob focuses his practice on advocating for policyholders in high-exposure property damage cases, insurance recovery claims, coverage disputes, construction-related claims, declaratory judgments, first & third-party claims, business interruption losses, indemnification, additional insured coverage, broker negligence, risk transfer, contractor/subcontractor liability, bad faith claims, contribution claims, breach of contract disputes, and general liability defense, as well as in litigating insurance coverage issues under several policy lines including homeowners, commercial liability, excess/umbrella, businessowners, cargo, freighting, and commercial auto policies.


Footnotes

1. N.Y. Ins. Law § 3105(a). ↩

2. N.Y. Ins. Law § 3105(b)(1); Lema v. Tower Ins. Co. of N.Y., 119 A.D.3d 657, 657–58 (2d Dept. 2014). ↩

3. Lema, 119 A.D.3d at 657–58 (“To establish the right to rescind an insurance policy, an insurer must show that its insured made a material misrepresentation of fact when he or she secured the policy.”) (quoting Interboro Ins. Co. v. Fatmir, 89 A.D.3d 993, 993–94 (2d Dept. 2011)). ↩

4. See, e.g., Dauria v. CastlePoint Ins. Co., 104 A.D.3d 406, 406 (1st Dept. 2013) (insurer rescinded homeowners policy after a fire at the insured premises); Lema, 119 A.D.3d at 658. ↩

5. Estiverne v. MIC Gen. Ins. Corp., 233 A.D.3d 844, 845, 223 N.Y.S.3d 705, 707 (2d Dept. 2024) (“‘[E]ven innocent misrepresentations, if material, are sufficient to allow an insurer to defeat recovery under the insurance contract.’”) (quoting Thandi v. Otsego Mut. Fire Ins. Co., 199 A.D.3d 849, 851 (2d Dept. 2021)). ↩

6. See, e.g., Multani v. Castlepoint Ins. Co., 221 A.D.3d 722, 724 (2d Dept. 2023); Almonte v. Castlepoint Ins. Co., 45 Misc. 3d 1218(A), 3 N.Y.S.3d 284 (Sup. Ct. N.Y. Cnty. 2014), aff’d, 140 A.D.3d 658 (1st Dept. 2016); Elshazly v. Castlepoint Ins. Co., 49 Misc. 3d 1216(A), 29 N.Y.S.3d 847, 2015 WL 7737920, at *3 (Sup. Ct. N.Y. Cnty. 2015). ↩

7. Dauria, 104 A.D.3d at 407 (building consisting of three dwelling units “does not fit within the policy definition of a covered ‘residence premises’”). ↩

8. Dauria, 104 A.D.3d at 407. ↩

9. Id. ↩

10. Hall v. Mountain Valley Indem. Co., No. 23-CV-2496 (LJL), 2024 WL 2943747, at *5 (S.D.N.Y. June 10, 2024) (the number of dwelling units in a building is determined by its structural configuration “and not by the number of families who reside in it”); see Dauria, 104 A.D.3d at 407. ↩

11. Hall, 2024 WL 2943747, at *5. ↩

12. Gottlieb v. Mountain Val. Indem. Co., 248 A.D.3d 687, 688 (1st Dept. 2026). ↩

13. Hermitage Ins. Co. v. LaFleur, 100 A.D.3d 426, 427 (1st Dept. 2012). ↩

14. Tower Ins. Co. of N.Y. v. Atuana, 127 A.D.3d 454, 454, 4 N.Y.S.3d 523 (1st Dept. 2015) (deed and city document indicating that the building was a two-family dwelling “were irrelevant”) (citing Hermitage, 100 A.D.3d at 427); Hall, 2024 WL 2943747, at *6. ↩

15. Gottlieb, 248 A.D.3d at 688 (citing Dauria, 104 A.D.3d at 407; Castlepoint Ins. Co. v. Jaipersaud, 127 A.D.3d 401, 401 (1st Dept. 2015)). ↩

16. Id. ↩

17. Id.; Dauria, 104 A.D.3d at 407; Lema, 119 A.D.3d at 658. ↩

18. Jaipersaud, 127 A.D.3d at 401; Gottlieb, 248 A.D.3d at 688. ↩

19. See Elshazly, 2015 WL 7737920, at *4. ↩

20. Id. (whether the interior door could be locked “is also of no moment”). ↩

21. See Canale v. Castlepoint Ins. Co., 64 Misc. 3d 1208(A), 2019 N.Y. Slip Op. 51073(U) (Sup. Ct. Bronx Cnty. 2019) (rooms outfitted with key-operated deadbolts). ↩

22. See Gottlieb, 248 A.D.3d at 688. ↩

23. See Dauria, 104 A.D.3d at 407. ↩

24. See Elshazly, 2015 WL 7737920, at *4 & n.5 (noting the insured’s concession that the second-floor door was “a normal interior bedroom door,” and holding that whether the second floor had an exterior entrance was “inconsequential”). ↩

25. See Gottlieb, 248 A.D.3d at 688. ↩

26. Dauria, 104 A.D.3d at 407; Lema, 119 A.D.3d at 658. ↩

27. Elshazly, 2015 WL 7737920, at *4. ↩

28. Id. ↩

29. Gottlieb, 248 A.D.3d at 688 (quoting Jaipersaud, 127 A.D.3d at 401). ↩

30. Id. ↩

31. Id. ↩

32. Id. (citing Mandelos v. Karavasidis, 86 N.Y.2d 767, 769 (1995)). ↩

33. Walker v. Tighe, 142 A.D.3d 549, 550–51 (2d Dept. 2016). ↩

34. N.Y.C. Admin. Code § 27-2004(a)(14); see Elshazly, 2015 WL 7737920, at *4 n.5 (record did not establish that the disputed area was arranged for the “exclusive use” of its occupants, as the Code definition requires). ↩

35. Dauria, 104 A.D.3d at 407. ↩

36. Lema, 119 A.D.3d at 658. ↩

37. Hermitage, 100 A.D.3d at 427. ↩

38. Jaipersaud, 127 A.D.3d at 401. ↩

39. Canale, 2019 N.Y. Slip Op. 51073(U). ↩

40. Gottlieb, 248 A.D.3d at 688. ↩

41. Walker, 142 A.D.3d at 550–51; see also Hall, 2024 WL 2943747, at *5 (describing Walker as rejecting the argument that the premises had more than four units when it was configured to have four units). ↩

42. Lee v. Union Mut. Fire Ins. Co., No. 20-CV-3191 (MKB), 2022 WL 3370086, at *6-7 (E.D.N.Y. Aug. 16, 2022), aff’d, 2023 WL 7014138 (2d Cir. 2023). ↩

43. Id. ↩

44. Alexi Home Design, Inc. v. Union Mut. Fire Ins. Co., 223 A.D.3d 449 (1st Dept. 2024). ↩

45. Hermitage, 100 A.D.3d at 427; Dauria, 104 A.D.3d at 407; Almonte, 140 A.D.3d at 659. ↩

Additional Insured Coverage, Part 2: The Duties to Defend and Indemnify, Applicable Policy Conditions/Exclusions, & Ins. Law 3420(d) Considerations

September 2026, by Aaron Jacob, Esq.

As discussed in Part 1, additional insureds are parties who are entitled to insurance coverage under someone else’s (the “named insured”) policy of insurance, and under New York law, they are entitled to the same type of coverage under the policy as the named insured.1

If a claim is filed against you, there are three things needed before you can enjoy full protection as an additional insured:

(1) that you qualify as an additional insured;
(2) that the duty to defend has been triggered; and
(3) that, if the claimant is ultimately successful on their claims, the duty to indemnify has been triggered.

Part 1 addressed the first requirement, i.e., proving that you qualify as an additional insured, including how to analyze the additional insured endorsement and its schedule, the level of contract formality the endorsement requires, privity of contract, and misnomer issues.

Once you have established additional insured status, the analysis turns to whether the underlying claim is covered under the named insured’s policy, i.e., whether the insurer has an obligation to provide coverage for the additional insured for the claim.

In this regard, there are two distinct duties of an insurance company with respect to providing additional insured coverage: (1) the duty to defend, and (2) the duty to indemnify. The former is an insurance company’s duty to hire attorneys to defend the additional insured in the lawsuit, while the latter is an insurance company’s duty to actually pay for the claimed injury, should the claimant be successful in the lawsuit.

This part addresses both duties, as well as the policy conditions and exclusions that can stop coverage for an additional insured for an event, and the requirements that Insurance Law § 3420(d) imposes on an insurer when it responds to a tender or denies coverage.

I. The Duty to Defend

It is well settled under New York law that an insurance company’s duty to defend is “exceedingly broad”2 and that “additional insureds are entitled to the same type of coverage under the policy as the named insured.”3 The duty to defend is broader than an insurer’s duty to indemnify.4

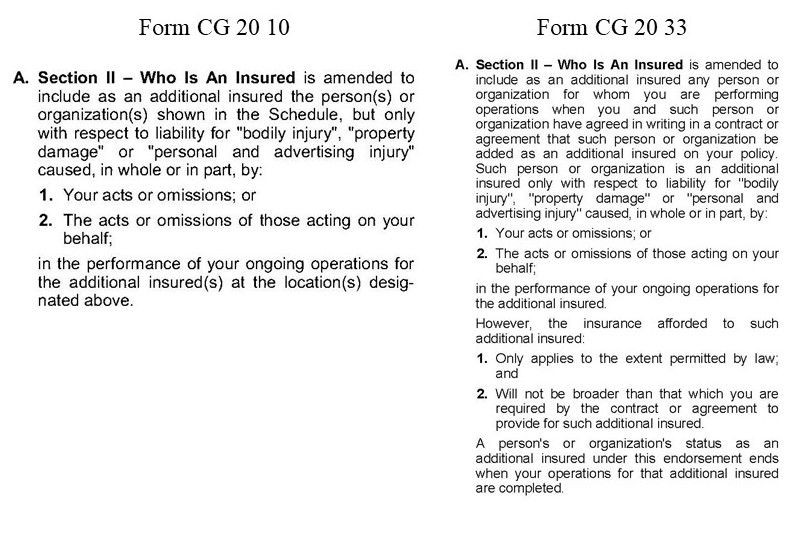
When applied to an additional insured, the scope of an insurer’s duty to provide additional insured coverage depends on the language of the endorsement that qualified that party to additional insured status. The following two policy forms are examples of endorsements that convey additional insured status and quantify the scope of such status:

Side-by-side comparison of Section A of Form CG 20 10 and Form CG 20 33, each covering liability caused, in whole or in part, by the named insured

As seen, these above common additional insured endorsements provide that there is additional insured coverage for liability “caused, in whole or in part,” by the “acts or omissions” of the named insured.5 This language was analyzed in Burlington Ins. Co. v NYC Tr. Auth., where the Court of Appeals held that “caused, in whole or in part” means “proximate cause.”6

Critically, the Burlington standard is applicable to whether an insurer has a duty to indemnify its insureds, but this standard does not have to be met (or proven) before the duty to defend is triggered. This is because the duty to defend an insured is a much lower bar, and so it is triggered by a claim having only a reasonable possibility of meeting the Burlington standard (i.e., that there is a reasonable possibility that the named insured was a proximate cause of the claimant’s injury).7

Therefore, an additional insured does not need to prove the named insured was an actual proximate cause of the claim/injury to be entitled to a defense, as that determination usually waits for a court or jury. Only the possibility of that finding is required to trigger a duty to defend.8 Once triggered, an insurer must defend the additional insured no matter how groundless, false or baseless the suit may be.9

The possibility of coverage, and therefore, the duty to defend, can be triggered in multiple ways, including even when a complaint doesn’t contain any allegations that the named insured was negligent, just so long as the insurer has knowledge of facts that establish a reasonable possibility of coverage.10 Some examples of where the duty to defend is triggered include:

(1) where the allegations of a complaint directly “suggest … a reasonable possibility of coverage” (e.g., the claimant says that they were injured while working for the named insured, or while working for a subcontractor of a named insured11);

(2) extrinsic evidence outside the complaint suggests the possibility of coverage (e.g., a contract provided to the insurer showing that the named insured was working on site on the day of injury); or

(3) even a third-party complaint that was filed by the additional insured, can trigger an insurer’s duty to defend12 (e.g., the additional insured sues the named insured for indemnification for the claimed injury).

The Burlington standard is commonly weaponized by insurers to avoid providing any coverage to its additional insureds, including providing a defense. This is because once an insurer steps in to defend its additional insured, it cannot withdraw from that defense without a court order13. A common excuse found in tender rejection letters is that the additional insured is not entitled to coverage because, for example, there is no proof that the claim/injury was caused by, in whole or in part, the acts or omissions of the named insured. This is a transparent misuse of the Burlington standard and should be challenged by any party seeking additional insured coverage.

Therefore, when tendering to an insurance company, or analyzing an insurer’s response to the tender, review and provide every available fact that would trigger the duty to defend, including:

(a) the pleadings (the named insured need not even be a party — for example, where the plaintiff is the named insured’s employee);

(b) discovery materials (deposition testimony, bills of particulars, etc.);

(c) third-party complaints — including one filed by the party seeking additional insured coverage itself; and

(d) known facts outside the four corners of the complaint, which can help trigger the duty to defend (e.g., a contract showing that the named insured was working on site at the time of the injury); and

(e) importantly, an insurer cannot rely on outside information to escape a defense obligation that the allegations otherwise trigger.14

Key takeaway: If an insurer disclaims based on the complaint alone, check whether discovery, a third-party complaint, or facts you already know about the loss would independently support the reasonable-possibility standard and put the insurer on notice of those facts in writing.

Because an additional insured’s right to a defense is based upon the reasonable possibility that the named insured was a proximate cause of the claimed injury, an insurer’s duty to defend an additional insured will end when the named insured is dismissed from the case, i.e., if and when the named insured is found not to have any liability for the alleged injury.15 However, the dismissal of the named insured (via summary judgment, directed verdict, or otherwise) cannot be used to retroactively alleviate an insurer’s duty to defend an additional insured.16 Therefore, even in cases where the named insured is eventually dismissed from an action, because the insurer would still have owed a duty to defend the additional insured up until the point of dismissal, an insurer would still be obligated to share or reimburse the additional insured’s defense costs up until the date of the named insured’s dismissal.17

Relatedly, in the event of a breach of the insurer’s duty to defend an additional insured, the additional insured’s damages are the expenses reasonably incurred by it in defending the action from the date of the insurer’s refusal to do so.18

II. The Duty to Indemnify

The partner of the duty to defend is the duty to indemnify. Indemnification of a claim means that the insurer will have to pay for the liability of its insureds, if the claimant is successful in the lawsuit. As discussed above, this means that if the additional insured endorsement uses the language “caused, in whole or in part”, then under the Burlington standard, the duty to indemnify will trigger where the named insured was at least a proximate cause of the liability. Proximate cause does not mean that the named insured was 100% liable for the injury, but only that the named insured was as little as 1% of the proximate cause of the injury.19 However, because proximate cause is a legal determination, it ultimately requires a judicial finding.

Notably, additional insured coverage may even include injuries that were caused by affirmative negligence on the part of the additional insured, so long as the named insured was a proximate cause of that injury.20 Moreover, in cases where the named insured is the employer of the injured claimant, the claimant’s own negligence can be imputed onto the named insured based on respondeat superior principles.21

There are some policy forms that use a different trigger than the Burlington language. For example, the term “arising out of”, as seen in the below form, is a broader, alternative trigger. “Arising out of” means “originating from, incident to, or having connection with.”22 This broader term requires only some causal relationship between the injury and the insured risk to trigger an insurer’s duties. 23

Form CG 20 11 04 13, Additional Insured – Managers or Lessors of Premises endorsement, using arising out of language

Under the “arising out of” language, the focus of the indemnification trigger is on the general nature of the operation during which the injury occurred, and you do not need to wait for a judicial determination of liability to trigger indemnity under this standard24. For example, where a claimant was injured while in the context of their employment with the named insured, a form with the language “arising out of” will be triggered regardless of whether the named insured was at fault.25

However, even this broader language will not trigger in every circumstance. Two examples where courts found no “arising out of” connection are as follows:

• A subcontractor had finished installing stairs and left the site; the general contractor conceded the staircase was merely the situs of the accident.26

• A bodily injury occurring outside the leased premises did not arise out of the named insured’s performance operations at the premises.27

III. Conditions and Exclusions

Even when a claim otherwise triggers additional insured coverage, certain policy terms, conditions, or exclusions can stop coverage for an event. Some of these conditions, terms, or exclusions may be imposed on the named insured, and some on the additional insured.

Conditions

Conditions in insurance policies can be express or implied.28 Express conditions are those agreed to and imposed by the parties themselves. In an insurance context, express conditions “must be literally complied with before a party to the contract may recover.” If a condition is a “condition precedent”, that condition must occur before an insurer has any obligation to perform its duties. More so, if there is a “condition precedent”, an insurer only needs to show that the condition was not met to avoid coverage, it does not need to show that it was prejudiced by the insured’s failure to meet that condition. A condition precedent usually but not always states that it is a condition precedent.

A common policy condition is that an insured must notify the insurer as soon as possible after it discovers or is notified of a claim, or that an insured must cooperate with the insurer. An example of a condition precedent is where a named insured must require its subcontractors to name it as an additional insured in their policies (and that the policy states that such requirement is a condition precedent).

That said, a named insured’s breach of a policy condition — including a condition precedent, such as late notice or lack of cooperation — is not grounds for disclaiming coverage to an additional insured.29 This means that if the named insured breached a policy condition by, for example, failing to notify the insurer of a claim until very late, an additional insured would still be entitled to coverage under that policy, even though the named insured was excluded from coverage for its failure to satisfy a condition.

Therefore, an insurer cannot point to the named insured’s own missteps in handling the claim to deny your separate coverage. (A breach of a condition by the additional insured itself is a different matter and can be grounds for denial.)

That said, some acts of the named insured may still invalidate coverage for the additional insured. Usually, these types of breaches invalidate the entire policy. An example of this would be if the named insured had a material misrepresentation in the application of the policy. If the insurer can prove this, and that they were prejudiced by that misrepresentation, they may be allowed to void or rescind the entire policy, ab initio, or stated otherwise, make it as if the policy was never issued in the first place.

If a policy is voided, ab initio, there would not be any additional insured coverage because there was no policy in the first place. That is because “additional insureds, by definition, must exist in addition to something; namely, the named insureds in a valid existing policy.”30

However, once a claim has been made, an insurer cannot rescind or void a policy by notice (to the named insured), because the rights of the insureds and additional insureds have already accrued.31 Therefore, once a claim has been made, an insurer would need a judicial determination before it would be allowed to rescind a policy.32

Exclusions

An exclusion is a policy term that seeks to exclude coverage for an otherwise covered event. These differ from conditions in that conditions can apply before coverage may be applied, while exclusions only apply after coverage for a claim is triggered. Exclusions can apply to additional insureds.

Whether an exclusion applies to an additional insured depends entirely on the policy’s wording, usually, whether the policy uses the language “the insured” or “any insured.”

• “The insured” limits a condition or exclusion to the particular insured it describes, or to the particular insured seeking coverage;

• “Any insured” (or “an insured”) binds all insureds to the consequences of any one insured’s act;

• The “named insured” is limited only to the named insured on the policy declarations.

These terms are commonly found in exclusions for an employee injury. For example, if an exclusion states that it applies for injury to an employee of the insured, the exclusion only bars coverage for the specific insured who actually employed the plaintiff, but it will not apply for an additional insured who was not the employer. If the same exclusion is written for an employee of “any insured”, then the exclusion bars coverage for all insureds, named and additional alike, if any of them employed the injured person.33 Therefore, some exclusions that would apply to one insured, may not apply to another.

Key takeaway: Always read the exact article of the exclusion the insurer is relying on. If it says “the insured” and the excluded conduct or relationship belongs only to the named insured, that exclusion should not reach you.

IV. Insurance Law § 3420(d) & Denial Letters

Insurance Law §3420(d) is a strong tool for any insured. This statute applies to any liability policy that provides coverage with respect to a claim arising out of the death or bodily injury of any person. This statute does not apply, however, to claims not for bodily injury/death, like for example, a claim for property damage or business interruption losses.

This provision outlines the requirements of an insurer’s response to a claim (arising out of bodily injury), such as a tender response, denial letter, reservation of rights, etc. Critically, “failure to comply with section 3420(d) precludes denial of coverage based on a policy exclusion.”34 So an insurer’s procedural defect under this provision can invalidate its entire position and waive its right to rely on policy exclusions.

• The basic requirement of Section 3420(d)(2) is that an insurer shall give written notice as soon as is reasonably possible of any denial letter to the insured and the injured person or any other claimant.

The determination of what is “as soon as reasonably possible” is generally fact specific, as not all the grounds for an exclusion will be available at the outset of a claim. Timeliness of insurer’s disclaimer of liability is measured from time when insurer first learns of grounds for disclaimer or denial of coverage35.

That said, “where the sole ground upon which the disclaimer is based is obvious from the face of the notice of claim and accompanying complaint, a delay of even 30 days has been held to be unreasonable.”36 If the grounds for a disclaimer are obvious, an insurer will have to provide an acceptable excuse for its delay, or else it will waive its right to deny the claim37.

An example of this is where an insurer denies coverage to a named insured, and months later, an additional insured tenders for coverage. If the insurer denies the additional insured tender on the same grounds as it denied the named insured’s claim, any excuse for a late denial letter will be insufficient as a matter of law38 (because the grounds for its disclaimer were already obvious by virtue of its disclaimer to the named insured).

• Section 3420(d)(2) requires that a disclaimer letter include, “with a high degree of specificity,” the ground or grounds on which the disclaimer is predicated.39 If a disclaimer letter does not specify a certain ground for its denial, the insurer will waive its right to rely on that ground for excluding coverage.40

A disclaimer letter must “identify the applicable policy exclusion and set forth the factual basis for the insurer’s position that the claim fell within a policy exclusion, with sufficient specificity to satisfy the statutory mandate and purpose.”41 That said, a small misquotation or a partial omission of the policy language of an exclusion does not invalidate it automatically, so long as the letter is otherwise sufficiently specific on the exclusion’s application.42 If an insurer denies coverage on one ground, then it will have waived all other grounds for denial (that were available at that time).

• Section 3420(d)(2) applies to additional insureds.43 Under New York law, additional insureds are entitled to the same protections as a named insured, including timely notice of disclaimer.44

• Section 3420(d)(2) requires the insurer to send disclaimer notice directly to the additional insured (or its counsel), and failure to do so precludes the insurer from disclaiming based on an exclusion.45 A letter sent only to the additional insured’s own insurer does not satisfy § 3420(d)(2).46

• If an additional insured receives the same copy of the disclaimer that was sent to the named insured, this letter can satisfy § 3420 — but only if that letter specifically addresses coverage for the additional insured (e.g., “therefore, there is no coverage available under the Policy for this claim for any party, including any additional insureds”).47 If a disclaimer only addresses the named insured’s own coverage, the disclaimer letter will not apply to the additional insured for 3420(d) purposes. For example, if the denial letter only addresses a late notice breach by the named insured, or an employee exclusion that only applies to the named insured, the letter will not satisfy the 3420(d) disclaimer requirements to an additional insured.48

• A reservation of rights letter does not constitute compliance with the requirements of section 3420(d).49

• 3420(d) applies whether the policy of insurance is primary or excess.50

• An insurer must still disclaim coverage as soon as reasonably possible even where the insured failed to provide timely notice of claim.51

Any failure on any of these points is an independent basis to challenge the denial, separate from the merits of coverage.

When tendering a claim on your behalf, confirm the package includes:

• Identification of who is tendering and on whose behalf;

• The named insured and the specific policy being tendered to (if available);

• The claim documentation (complaint, notice of loss, etc.);

• The contract or agreement connecting you to the named insured, matched against the endorsement’s exact requirement (contract vs. written contract vs. executed written contract, and scheduled vs. blanket basis); and

• A letter invoking the triggering language for the duty to defend with supporting facts (from the pleadings, discovery, or otherwise).

* * *

Aboulafia Law Firm LLC works exclusively on behalf of policyholders and has decades of experience fighting insurance companies. Whether you are dealing with a residential or commercial property claim, we are ready to help you. If you are seeking to obtain additional insured coverage or are dealing with a tender, don’t navigate the complex claims process alone. For assistance on your insurance claim, please contact us.

The opinions expressed are those of the author(s) and do not necessarily reflect the views of the firm, its clients, or any of its or their respective affiliates. This article is for general information purposes and is not intended to be and should not be taken as legal advice.

Aaron Jacob is a senior associate at Aboulafia Law Firm LLC. Mr. Jacob is a skilled litigation and coverage attorney and has extensive experience representing commercial and private clients involved in property damage and insurance coverage claims in complex state and federal court matters.

Mr. Jacob focuses his practice on advocating for policyholders in high-exposure property damage cases, insurance recovery claims, coverage disputes, construction-related claims, declaratory judgments, first & third-party claims, business interruption losses, indemnification, additional insured coverage, broker negligence, risk transfer, contractor/subcontractor liability, bad faith claims, contribution claims, breach of contract disputes, and general liability defense, as well as in litigating insurance coverage issues under several policy lines including homeowners, commercial liability, excess/umbrella, businessowners, cargo, freighting, and commercial auto policies.


Footnotes

1. Pecker Iron Works of N. Am., Inc. v. Travelers Ins. Co., 99 N.Y.2d 391 (2003). ↩

2. Auto. Ins. Co. of Hartford v. Cook, 7 N.Y.3d 131, 137 (2006). ↩

3. Pecker Iron Works of N. Am., Inc. v. Travelers Ins. Co., 99 N.Y.2d 391 (2003) ↩

4. Auto. Ins. Co. of Hartford v. Cook, 7 N.Y.3d at 137. ↩

5. An alternative trigger to “caused, in whole or in part,” is “arising out of”, discussed later. ↩

6. Burlington Ins. Co. v NYC Tr. Auth., 57 N.Y.S.3d 85 (2017). ↩

7. Indian Harbor Ins. Co. v. Alma Tower, LLC, 87 N.Y.S.3d 9, 10 (1st Dept. 2018) (“because there is a reasonable possibility that [the named insured] proximately caused the injury…”); Live Nation Mktg., Inc. v. Greenwich Ins. Co., 188 A.D.3d 422, 423, 135 N.Y.S.3d 87, 89 (1st Dept. 2020). ↩

8. Citizens Ins. Co. of Am. v. Am. Ins. Co., 130 N.Y.S.3d 289, 290 (1st Dept. 2020) ↩

9. Automobile Ins. Co. of Hartford v. Cook, 850 N.E.2d 1152, 1155 (2006). ↩

10. WDF Inc. v. Harleysville Ins. Co. of New York, 146 N.Y.S.3d 128 (1st Dept. 2021); Indian Harbor Ins. Co. v. Alma Tower, LLC, 87 N.Y.S.3d 9 (1st Dept. 2018) ↩

11. Exeter Bldg. Corp. v. Scottsdale Ins. Co., 913 N.Y.S.2d 733 (2d Dept. 2010) ↩

12. Automobile Ins. Co. of Hartford v. Cook, 850 N.E.2d at 1155; see also, Wesco Ins. Co. v. Hellas Glass Works Corp., 2020 NY Slip Op 06975, ¶ 1, 188 A.D.3d 621, 621, 132 N.Y.S.3d 758, 758 (App. Div. 1st Dept. 2020); One Reason Rd., LLC v. Seneca Ins. Co., Inc., 83 N.Y.S.3d 235, 238 (2nd Dept. 2018); All State Int. Demolition Inc. v. Scottsdale Ins. Co., 92 N.Y.S.3d 256, 257 (1st Dept. 2019); Indian Harbor Ins. Co. v. Alma Tower, LLC, 165 AD3d 549, 549 (1st Dept 2018); Greater New York Mut. Ins. Co. v. State Natl. Ins. Co., Inc., 120 N.Y.S.3d 578 (N.Y. Sup. Ct. 2019); Travelers Prop. Cas. Co. of Am. v. Harleysville Ins. Co. of N.Y., 128 N.Y.S.3d 154 (Sup. Ct. 2020) (rejecting an insurer’s argument that a third-party complaint cannot be relied upon to establish a duty to defend). ↩

13. Seye v. Sibbio, 821 N.Y.S.2d 473 (2d Dept. 2006) ↩

14. Fitzpatrick v. Am. Honda Motor Co., Inc., 575 N.E.2d 90 (1991). ↩

15. Monadnock Const., Inc. v. DiFama Concrete, Inc., 896 N.Y.S.2d 107, 108 (2d Dept. 2010) ↩

16. Allied World Assurance Co. (U.S.) Inc. v. Aspen Specialty Ins. Co., 139 N.Y.S.3d 816, 817 (1st Dept. 2021) ↩

17. Id.; see also, City of Niagara Falls v. Merchants Ins. Group, 824 N.Y.S.2d 841, 842–43 (4th Dept. 2006) ↩

18. Nat’l Union Fire Ins. Co. of Pittsburgh, PA v. Greenwich Ins. Co., 103 A.D.3d 473, 474, 962 N.Y.S.2d 9, 11 (1st Dept. 2013) ↩

19. Burlington Ins. Co. v NYC Tr. Auth., 57 N.Y.S.3d 85 (2017); Starr Indem. & Liab. Co. v. Excelsior Ins. Co., 516 F. Supp. 3d 337, 349 (S.D.N.Y. 2021) (NY law) ↩

20. Breeze Natl., Inc. v. Cent. Sur. Co., 96 N.Y.S.3d 56, 57 (1st Dept. 2019); E.E. Cruz & Co., Inc. v. Axis Surplus Ins. Co., 87 N.Y.S.3d 173, 175 (1st Dept. 2018). ↩

21. Guiga v. JLS Const. Co., Inc., 685 N.Y.S.2d 1, 2 (1st Dept. 1998); Mercado v. Caithness Long Island LLC, 961 N.Y.S.2d 424, 427 (1st Dept. 2013) ↩

22. Regal Constr. Corp. v National Union Fire Ins. Co. of Pittsburgh, PA, 15 NY3d 34, 38, 930 N.E.2d 259, 904 N.Y.S.2d 338 (2010) ↩

23. Id. ↩

24. Hunter Roberts Const. Group., LLC v. Arch Ins. Co., 75 AD3d 404, 408 (1st Dept. 2010) ↩

25. Id. ↩

26. Worth Const. Co., Inc. v. Admiral Ins. Co., 888 N.E.2d 1043 (2008). ↩

27. Christ the King Regl. High Sch. v. Zurich Ins. Co. of N.A., 937 N.Y.S.2d 290, 294 (2nd Dept. 2012). ↩

28. Oppenheimer & Co. v. Oppenheim, Appel, Dixon & Co., 636 N.Y.S.2d 734, 660 N.E.2d 415, 418 (1995); Seaport Park Condo. v. Greater New York Mut. Ins. Co., 828 N.Y.S.2d 381, 384 (1st Dept. 2007). ↩

29. 233 E. 17th St., LLC v. L.G.B. Dev., Inc., 913 N.Y.S.2d 110, 112 (2nd Dept. 2010). ↩

30. Admiral Ins. Co. v. Joy Contractors, Inc., 19 N.Y.3d 448, 461 (2012) ↩

31. Fed. Ins. Co. v. Kozlowski, 792 N.Y.S.2d 397, 402 (1st Dept. 2005); Kiss Const. NY, Inc. v. Rutgers Cas. Ins. Co., 877 N.Y.S.2d 253, 256 (1st Dept. 2009); Indian Harbor Ins. Co. v. Alma Tower, LLC, 87 N.Y.S.3d 9, 10 (1st Dept. 2018) ↩

32. Id. ↩

33. Moleon v. Kreisler Borg Florman Gen. Const. Co., Inc., 758 N.Y.S.2d 621, 624 (1st Dept. 2003); Sixty Sutton Corp. v. Illinois Union Ins. Co., 825 N.Y.S.2d 46, 49 (1st Dept. 2006); Soho Plaza Corp. v. Birnbaum, 969 N.Y.S.2d 96, 100 (2d Dept. 2013). ↩

34. Matter of Worcester Ins. Co. v Bettenhauser, 95 NY2d 185, 188, 734 N.E.2d 745, 712 N.Y.S.2d 433 (2000) ↩

35. Allcity Ins. Co. v Jimenez, 78 N.Y.2d 1054, 576 N.Y.S.2d 87, 581 N.E.2d 1342, (1991); Plotkin v. Republic-Franklin Ins. Co., 177 A.D.3d 790, 793-94, 113 N.Y.S.3d 133, 138 (2nd Dept. 2019) ↩

36. Gagosian Gallery, Inc. v. Eurostruct, Inc., 814 N.Y.S.2d 890 (N.Y. Sup. Ct. 2005) citing West 16th Street Tenants Corp. v. Pub. Service Mut. Ins. Co., 736 N.Y.S.2d 34 (1st Dept. 2002). ↩

37. Id., see also AIU Ins. Co. v. Veras, 942 N.Y.S.2d 532, 533 (1st Dep’t 2012); Sirius Am. Ins. Co. v. Vigo Const. Com., 852 N.Y.S.2d 176, 178 (2d Dep’t 2008) (finding 34-day delay unreasonable as a matter of law where no explanation was provided). ↩

38. Plotkin v. Republic-Franklin Ins. Co., 177 A.D.3d 790, 793-94, 113 N.Y.S.3d 133, 138 (2nd Dept. 2019) citing Stout v 1 E. 66th St. Corp., 90 A.D.3d 898, 902, 935 N.Y.S.2d 49, 54 (2nd Dept 2011) ↩

39. Gen. Accident Ins. Grp. v. Cirucci, 46 N.Y.2d 862, 414 N.Y.S.2d 512, 387 N.E.2d 223, 225 (1979). ↩

40. Id., see also Zappone v. Home Ins. Co., 55 N.Y.2d 131, 135 (1982) ↩

41. Adams v. Perry’s Place, 168 A.D.2d 932, 564 N.Y.S.2d 1019, 1019 (1990). ↩

42. Id. ↩

43. See Sierra v 4401 Sunset Park, LLC, 957 N.Y.S.2d 219 (2d Dept 2012), affd 25 N.E.3d 921 (2014); Matter of Worcester Ins. Co. v Bettenhauser, 95 NY2d 185, 188, 734 N.E.2d 745, 712 N.Y.S.2d 433 (2000). ↩

44. Id. ↩

45. Sierra v. 4401 Sunset Park, LLC, 24 N.Y.3d 514, 2 N.Y.S.3d 8 (2014). ↩

46. Id. (“The obligation imposed by the Insurance Law is to give timely notice to the mutual insureds … not to … another insurer”). ↩

47. Valiant Ins. Co. v. Utica First Ins. Co., 185 A.D.3d 435, 436 (1st Dept. 2020) ↩

48. Pofi Constr. Corp. v. Rutgers Cas. Ins. Co., 137 N.Y.S.3d 314, 315 (1st Dept. 2020); Endurance Am. Specialty Ins. Co. v. Utica First Ins. Co., 17 N.Y.S.3d 401, 403 (1st Dept. 2015). ↩

49. Zappone v. Home Ins. Co., 55 N.Y.2d 131, 135 (1982). ↩

50. Id. ↩

51. First Fin. Ins. Co. v. Jetco Contracting Corp., 801 N.E.2d 835, 837 (2003). ↩

Additional Insured Coverage Part 1: Analysis of Policy Endorsements and Contract Requirements

September 2026, by Aaron Jacob, Esq.

Risk protection and liability transfer are of critical importance to any property owner, general contractor, lessor, licensor, or other businesses that contract with subcontractors, vendors, lessees, licensees, or other downstream entities. Most contracts and subcontracts already require the downstream party to carry insurance and name the upstream party as an “additional insured” on their insurance policy as well as contain indemnification rights. Often, you will also get a certificate of insurance from that party, purportedly showing that they procured the required coverage.

However, if a claim ever gets filed, many parties suddenly find themselves without the contracted-for protection and find that the certificate of insurance is not worth the paper it is written on. Then, the upstream party has to use its own insurance to defend them against a claim, or if they are uninsured, pay out of pocket for counsel. This is at least partly because insurers routinely look for reasons to deny additional insured requests and find opportunities to deny tenders or indemnification demands due to a handful of technicalities in contracts or policies that come up repeatedly.

Drafting the contract carefully and securing the correct policy initially alleviates many of the issues but also understanding how you can trigger additional insured coverage and/or indemnification rights, or challenge an insurer’s response after the fact, can be incredibly helpful.

An analysis of common additional insured endorsements under New York law is below, including what a party needs to prove to qualify as an additional insured, what to include in your tender, and what to require up front when drafting the contract so a future tender doesn’t run into an avoidable problem.

What Are Additional Insureds?

Additional insureds are parties who are entitled to insurance coverage under someone else’s (the “named insured”) policy of insurance. A classic example is an owner of a property requiring that they are named as an additional insured on a policy of insurance held by a contractor who is performing construction work at the owner’s property. This way, if someone is injured during construction as a result of the contractor’s work, and the injured party sues the owner, the owner can look to the contractor’s insurer for insurance coverage to defend the claims.

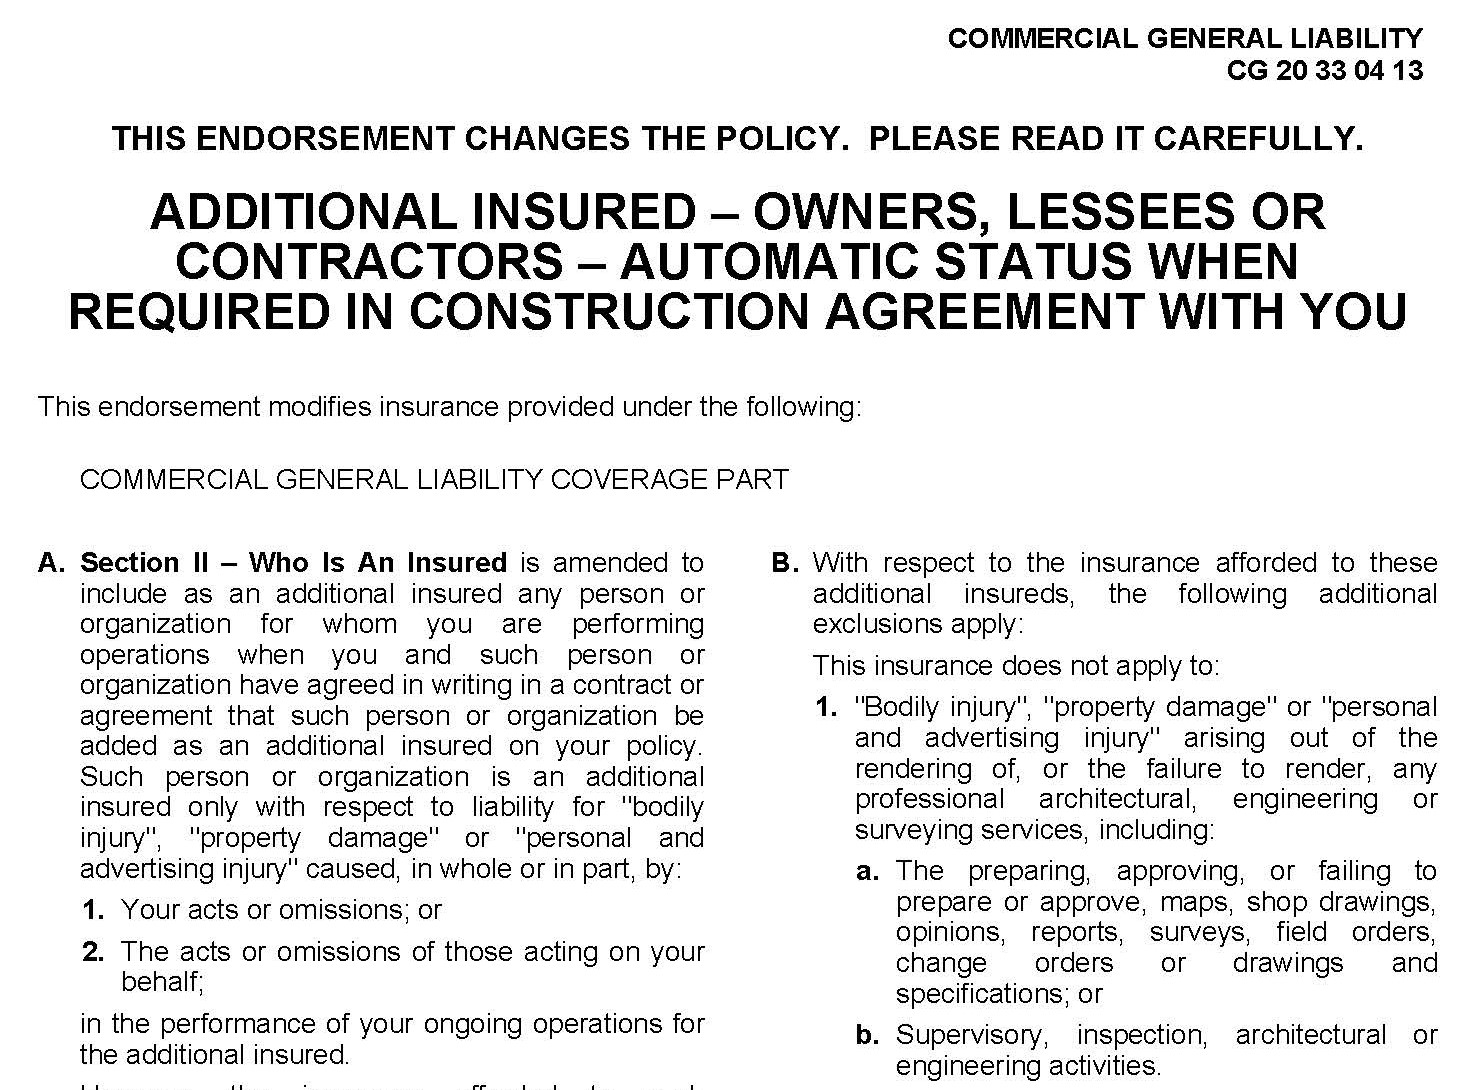
Under New York law, additional insureds are entitled to the same type of coverage under the policy as the named insured.1 Similarly, the standard for determining whether an additional insured is entitled to coverage for a claim is the same standard as determining whether a named insured is entitled to coverage.2

However, there are many types of policy forms and endorsements that purport to provide additional insured coverage, but they are not all equal in how easy it is to qualify for that coverage. If a claim is filed against you, there are three things needed before you can enjoy full protection as an additional insured.

(1) that you qualify as an additional insured;
(2) that the duty to defend has been triggered; and
(3) that, if the claimant is ultimately successful on their claims, the duty to indemnify has been triggered.

In New York, there are also laws that protect insureds from certain acts by an insurance company, including a late response (Ins. Law 3420(d)), discussed in Part 2 of this article. This Part 1 addresses the first requirement, i.e., proving that you qualify as an additional insured.

The Complete Tender Package

Proving you qualify as an additional insured

The burden is on the party seeking additional insured coverage to establish entitlement in the first instance.3 Because that burden falls on you, the tender should be drafted so that the insurer has no room to claim the proof was insufficient. A complete tender package should include:

(a) the identity of who is sending the tender (and on whose behalf) — you, your attorney, or your own insurer;

(b) the identity of the named insured and the policy under which additional insured coverage is sought;

(c) information about the underlying claim, with supporting documents — e.g., the summons and complaint, or a claimant’s notice of loss; and

(d) documentation connecting the named insured to the claim and to your right to additional insured status — typically the contract between you and the named insured requiring the additional insured endorsement.

Key takeaway: Before you send the tender, compare the underlying contract against the specific requirements of the additional insured endorsement itself (discussed below). A mismatch between the two is a very common reason insurers reject a tender — catching it before you send the package lets you gather better proof instead of receiving a denial. And if you are instead the party requiring this coverage from a subcontractor or vendor, this is also exactly what to fix at the drafting stage: keep the fully executed contract and the actual additional insured endorsement — not just a certificate of insurance — in the project file for the life of the project plus the statute of limitations, so this step is never the reason a future tender fails.

The Additional Insured Endorsement

The two most common issues in qualifying for additional insured coverage arise from either the language of the contract, or the language of the additional insured endorsement in the policy. Identifying which additional insured endorsement is actually included in the named insured’s policy and what you must show to qualify as an additional insured depends entirely on its wording.

One of the most common additional insured endorsement forms in construction liability policies is “CG 20 10”, shown below:

Form CG 20 10 04 13, Additional Insured – Owners, Lessees or Contractors – Scheduled Person or Organization endorsement

As seen above, under this endorsement4, a party will qualify as an additional insured if they are listed in the schedule. Often the schedule will identify the party directly. However, the schedule may also state – “as required by contract” or “as required by written contract with the insured.” If the party satisfies being identified in the schedule, then they will qualify as additional insured and be entitled to coverage for any claim that was “caused by, in whole or in part”, the “acts or omissions” of the named insured or the acts and omissions of those working on the named insured’s behalf. All these elements are discussed below.

Key takeaway: If you are the party requiring this coverage from a subcontractor or vendor, don’t leave the choice of form to the subcontractor’s broker. Specify the actual endorsement (e.g., CG 20 10, current edition) in the subcontract and require it to cover both ongoing and completed operations — not just the active construction period. That matters most for a property owner who may face a claim well after the project is finished.

Analyzing the Schedule

The Schedule used in the additional insured endorsement usually lists one of a few options.

1. Scheduled Basis — the additional insured is specifically listed on the endorsement itself or on the declarations page. Four examples below:

Example endorsement schedule listing four additional insureds by name: General Contracting Corp.; The Property Owner Inc., its officers, agents, and affiliates; The State of New York; and The Metropolitan Transportation Authority

2. Automatic/Blanket Basis — additional insured status arises automatically whenever it is required by an outside agreement with the named insured. Three examples:

Example endorsement schedule with three blanket entries: per executed written contract prior to a loss; where required by written contract prior to a loss; and for any person or organization you agreed with in a contract to add as an additional insured

Does the Party Seeking Coverage Fall Within the Schedule?

If a party’s status depends on an outside agreement with the named insured (e.g., where required by contract), then the underlying agreement must satisfy the level of formality the schedule requires.

New York courts draw sharp distinctions between the terms “contract,” a “written contract,” and an “executed written contract.”5 Misjudging which tier applies is a common and avoidable reason that a tender fails.

(a) Satisfying an “agreement” or “contract”

At the base level, when the endorsement only requires there to be a “contract” or “agreement” requiring additional insured coverage, there need only be a binding contract requiring the named insured to procure additional insured coverage, in place on the date of loss. Some examples of what satisfies this term are as follows:

• A vendor’s profile on a commercial contractor directory, or a client’s vendor bulletin stating the client is typically listed as an additional insured, is not itself an agreement or contract to do so.6

• A proposal, estimate, or letter of intent (“LOI”) can qualify if the named insured and the other party showed intent to be bound — for example, by starting work — even if a more detailed agreement was meant to follow.7

• If a document is merely an “agreement to agree,” there is no agreement, as these documents typically include an express reservation that neither party is bound until a more formal agreement is signed.8

• A certificate of insurance listing you as an additional insured is not, itself, an agreement to procure that coverage.9

Key takeaway: If your agreement is informal or unsigned, look for conduct showing both sides treated themselves as bound — the sub mobilized on site, submitted invoices referencing the agreement, or was paid under it. That conduct can be enough on its own. If instead you are the one requiring this coverage from a sub, don’t build the program around a certificate of insurance: a COI is evidence of a policy, not proof of additional insured status, and is not itself an agreement to provide it. Always obtain and review the actual endorsement.

(b) Satisfying a “written contract”

The second tier of agreement requires that there be a “written contract”. Under New York law, a “written contract” must be in writing, but does not need to be signed.10

• An oral agreement or handshake will not satisfy “written contract,” even if memorialized in writing after the date of loss.11

• A certificate of insurance is not a “written contract” because it does not confer coverage.12

• A proposal or LOI (letter of intent) that qualifies as a contract at all will also satisfy “written contract.”13

• A purchase order with no signature lines can satisfy “written” — but not “signed” or “executed.”14

Key takeaway: Don’t assume you need a signature just because the endorsement says “written contract.” An unsigned but written proposal or purchase order can be enough at this tier — read the endorsement’s exact wording before assuming more is required.

(c) Satisfying an “executed written contract” or “signed written contract”

At this tier, executed means signed. If there is one signature line, this must be signed by the party seeking additional insured coverage. If there are two signature lines, both parties must sign. This is the tier where tenders often fail on a technicality.

• A proposal letter not signed by the construction manager seeking additional insured status did not satisfy “executed written contract.”15

• A contract with two signature lines but only one signature is not “executed.”16

• A purchase order with no signature lines cannot be a “signed/executed written contract.”17

Key takeaway: If the endorsement requires an executed or signed written contract, get the fully signed contract into the file before there’s a loss, as an unsigned proposal or a one-sided signature block will not be cured later, no matter how clear everyone’s intent was. If you are the one drafting the subcontract, build this in from the start: require the subcontract to be fully signed by both parties before the sub begins work on site, and don’t let work start on a proposal or purchase order alone if the endorsement you’re relying on requires an executed contract.

Other Contract Considerations – “Privity of Contract”

(a) Is “Privity of Contract” needed?

Example: a property owner hires a general contractor for roofing work (the “contract”). The general contractor then hires a subcontractor (the “subcontract”). The contract requires the general contractor to provide additional insured coverage to the property owner, and that the general contractor must require any subcontractor to name the owner as an additional insured. The subcontract requires the subcontractor to provide additional insured coverage for both the general contractor and the property owner. The property owner is not a party to the subcontract.

Under Form CG 20 10 (above), based on qualifying under a satisfying “written agreement”, both the general contractor and the owner are entitled to coverage under the subcontractor’s insurance. 18

Under Form CG 20 33, a stricter endorsement, only the general contractor would be entitled to coverage. The owner is not, because this endorsement requires direct privity of contract between the subcontractor and the party seeking additional insured coverage, which does not include the owner.19

Form CG 20 33 04 13, Additional Insured – Owners, Lessees or Contractors – Automatic Status When Required in Construction Agreement With You endorsement

New York courts have held that if the policy contains a CG 20 33-type endorsement and the party seeking additional insured status has no written agreement directly with the purchaser of the insurance, there is no coverage, even if some other agreement provides that the supposed additional insured will receive it.20 This is because the endorsement states that additional insured status is only provided when there is a written contract “with you”, and “you” being the named insured. Because, in the above example, the owner does not have a written contract “with you” (i.e., the subcontractor), it does not qualify as an additional insured.

Key takeaway: If you are an owner or upper-tier contractor without a direct agreement with the sub whose policy you’re tendering to, this is the gap insurers commonly exploit. At the drafting stage, require CG 20 10 or an equivalent form that does not condition coverage on privity, or get a direct written agreement with the sub. Do not rely on a CG 20 33-type form in a multi-tier structure where you have no direct contract with the subcontractors or other downstream parties. If the loss has already happened and your contract with the sub only ties to CG 20 33, look for any direct writing, even an informal one, between you and the subcontractor before conceding the point.

Contract Issues: Does the contract require additional insured coverage?

Generally, the provision requiring the named insured to procure coverage for you in the underlying contract must be express and specifically stated.21 These following cases show how easily a generic insurance clause can fail to do the job:

(1) No coverage, where a contract requiring the named insured to purchase several forms of insurance for itself, without expressly requiring it to name the owner as an additional insured on its general liability coverage, does not create additional insured coverage.22

(2) No coverage, where a hold-harmless agreement with no requirement to name the owner as an additional insured does not create coverage.23

(3) No coverage, where an agreement to obtain liability insurance in one’s own right and separately hold the other party harmless does not create coverage.24

(4) No coverage, where a requirement of “general liability insurance” with “certificates to follow” only requires the named insured to hold its own coverage and provide proof of it — it does not create additional insured status.25

(5) No coverage, where a certificate of insurance listing the parties as additional insureds, standing alone, does not create coverage.26

(6) No coverage, where a general clause incorporating the insurance provisions of a prime contract by reference did not create coverage here — though this can be enough if the prime contract itself has specific, on-point terms for the subcontractor.27

(7) No coverage, where a blanket agreement requiring coverage for “specified owners” did not cover an owner who was not actually specified, even though it owned the property.28

(8) No coverage, where a requirement that the named insured provide certificates of insurance from its subs listing the owner as an additional insured, without more, was not enough.29

(9) No coverage, where a clause making insurance procurement a condition of an owner’s right to withhold payment — rather than an independent, express obligation — did not create coverage.30

(10) Coverage found, where a contract requiring a “certificate of insurance clearly setting forth the coverage for the equipment and naming [the party] as loss payee and additional insured” was specific enough.31

Key takeaway: Every “no coverage” result above traces back to a contract clause that was vague, generic, or conditional. When you are reviewing an existing contract before a loss or drafting the next one, insist on language that expressly says the contractor/subcontractor “shall name [Owner/GC] as an additional insured” under a specific CGL form, on a primary and noncontributory basis. General language just requiring “insurance” will not suffice. A clause incorporating “the insurance requirements of the prime contract” by reference can work, but only if the referenced document actually contains specific, on-point additional insured language for that subcontractor; don’t assume a passing reference is enough.

Identity of party issues — misnamed parties on the contract, policy, or schedule

New York is generally forgiving of naming errors, and courts have held that effectively naming the insured or additional insured is enough. The policy, schedule, or contract does not need to be 100% accurate, so long as it is clearly the same party. The following cases illustrate insurers trying to deny tenders over a technical misnomer, without success:

(1) An insurer could not withhold coverage over an error listing “Court Tobacco Co.” rather than “Court Tobacco Stores, Inc.”32

(2) A policy naming the “New York State Department of Social Welfare Commission for the Blind” was equivalent to naming the State of New York.33

(3) No meaningful difference between “Stoncor Group” and its trade name “Stonhard Corp.”34

(4) A subcontract requiring coverage for “Stellar Mechanical Services of N.Y. II” satisfied the requirement for “Stellar Mech. Services of New York, Inc.”35

(5) An insurer could not withhold coverage over a misidentified named insured where the intent to cover the project’s risk was clear.36

(6) An insurer’s obligation to cover a mortgage holder’s risk applied even though the mortgage holder was misidentified in the contract.37

(7) Even though only the former landlord was listed as the additional insured, the current landlord was entitled to coverage where the named insured had agreed to insure the landlord and the policy expressly covered the landlord’s risk.38

Key takeaway: If you are the one drafting the subcontract, get entity names right — but don’t panic over minor variations that do slip through. New York courts will look past immaterial misnomers so long as the intended party is clear, as the cases above show.

Once you have established that you qualify as an additional insured, the analysis turns to whether the insurer’s duty to defend, and ultimately its duty to indemnify, has been triggered. Those issues, along with the policy conditions and exclusions that can stop coverage for an event and the requirements Insurance Law § 3420(d) imposes on an insurer when it responds to a tender or denies coverage, are addressed in Part 2 of this article.

If you are drafting or negotiating a contract with a contractor, subcontractor, or any downstream party, build these protections into the contract before the work or contract begins:

• Express, specific language that the subcontractor “shall name [Owner/GC] as an additional insured”, on a primary and noncontributory basis, with specific limits. Make sure not to only use generic language requiring only that the sub “maintain insurance”;

• A fully executed contract, signed by both parties before work begins;

• State the specific additional insured endorsement form (e.g., CG 20 10), covering both ongoing and completed operations; and

• Ensure that additional downstream entities do not require direct privity-of-contract, such as in a CG 20 33-type endorsement.

* * *

Aboulafia Law Firm LLC works exclusively on behalf of policyholders and has decades of experience fighting insurance companies. Whether you are dealing with a residential or commercial property claim, we are ready to help you. If you are seeking to obtain additional insured coverage or are dealing with a tender, don’t navigate the complex claims process alone. For assistance on your insurance claim, please contact us.

The opinions expressed are those of the author(s) and do not necessarily reflect the views of the firm, its clients, or any of its or their respective affiliates. This article is for general information purposes and is not intended to be and should not be taken as legal advice.

Aaron Jacob is a senior associate at Aboulafia Law Firm LLC. Mr. Jacob is a skilled litigation and coverage attorney and has extensive experience representing commercial and private clients involved in property damage and insurance coverage claims in complex state and federal court matters.

Mr. Jacob focuses his practice on advocating for policyholders in high-exposure property damage cases, insurance recovery claims, coverage disputes, construction-related claims, declaratory judgments, first & third-party claims, business interruption losses, indemnification, additional insured coverage, broker negligence, risk transfer, contractor/subcontractor liability, bad faith claims, contribution claims, breach of contract disputes, and general liability defense, as well as in litigating insurance coverage issues under several policy lines including homeowners, commercial liability, excess/umbrella, businessowners, cargo, freighting, and commercial auto policies.


Footnotes

1. Pecker Iron Works of N. Am., Inc. v. Travelers Ins. Co., 99 N.Y.2d 391 (2003). ↩

2. Id., see also BP Air Conditioning Corp. v. One Beacon Ins. Grp., 8 N.Y.3d 708, 715 (2007). ↩

3. Tribeca Broadway Associates, LLC v. Mt. Vernon Fire Ins. Co., 774 N.Y.S.2d 11, 13 (1st Dept. 2004). ↩

4. This specific endorsement form is usually the most lenient and advantageous for additional insureds. ↩

5. Chipotle Mexican Grill, Inc. v. RLI Ins. Co., 158 N.Y.S.3d 201, 205 (2nd Dept. 2021) (“agreement” or “contract”); Zurich Am. Ins. Co. v. Endurance Am. Speciality Ins. Co., 43 N.Y.S.3d 40, 41 (1st Dept. 2016) (“written contract”); Nicotra Group, LLC v. Am. Safety Indem. Co., 850 N.Y.S.2d 455, 457 (1st Dept. 2008) (“executed written contract”). ↩

6. Chipotle Mexican Grill, Inc. v. RLI Ins. Co., 158 N.Y.S.3d 201, 205 (2nd Dept. 2021). ↩

7. Bed Bath & Beyond Inc. v. IBEX Const., LLC, 860 N.Y.S.2d 107, 109 (1st Dept. 2008); Netherlands Ins. Co. v. Endurance Am. Specialty Ins. Co., 66 N.Y.S.3d 441, 442 (1st Dept. 2018). ↩

8. Emigrant Bank v. UBS Real Est. Securities, Inc., 854 N.Y.S.2d 39, 41 (1st Dept. 2008). ↩

9. Chipotle, 158 N.Y.S.3d at 205. ↩

10. Zurich Am. Ins. Co. v. Endurance Am. Speciality Ins. Co., 43 N.Y.S.3d 40, 41 (1st Dept. 2016). ↩

11. Landsman Dev. Corp. v. RLI Ins. Co., 53 N.Y.S.3d 428, 430 (4th Dept. 2017). ↩

12. ALIB, Inc. v. A. Cas. Ins. Co., 861 N.Y.S.2d 28, 29 (1st Dept. 2008). ↩

13. Bed Bath & Beyond, 860 N.Y.S.2d at 108–09. ↩

14. Zurich Am. Ins. Co., 43 N.Y.S.3d at 41. ↩

15. Nicotra Group, LLC v. Am. Safety Indem. Co., 850 N.Y.S.2d 455, 457 (1st Dept. 2008); Natl. Abatement Corp. v. Natl. Union Fire Ins. Co. of Pittsburgh, PA, 824 N.Y.S.2d 230, 232 (1st Dept. 2006). ↩

16. Cusumano v. Extell Rock, LLC, 86 A.D.3d 448, 449, 927 N.Y.S.2d 627 (1st Dept. 2011). ↩

17. Zurich Am. Ins. Co., 43 N.Y.S.3d at 41. ↩

18. Direct privity of contract can also be required under Form CG 20 10, depending on the language used in the schedule. E.g., if the schedule purports to only provide coverage for people that “you agreed with” in a contract, some courts may interpret that language as requiring direct privity of contract. Under this language, the analysis is comparable to CG 20 33. ↩

19. See, above. ↩

20. See Gilbane Bldg. Co./TDX Constr. Corp. v St. Paul Fire & Mar. Ins. Co., 143 AD3d 146, 152, 38 NYS3d 1 [1st Dept 2016], aff’d 31 NY3d 131, 74 NYS3d 162, 97 NE3d 711 [2018]; AB Green Gansevoort, LLC v Peter Scalamandre & Sons, Inc., 102 AD3d 425, 426–427, 961 NYS2d 3 [1st Dept 2013]. ↩

21. Trapani v. 10 Arial Way Associates, 755 N.Y.S.2d 396, 398 (2nd Dept. 2003). ↩

22. 140 Broadway Prop. v. Schindler Elevator Co., 901 N.Y.S.2d 292, 293 (2d Dept. 2010). ↩

23. Hargob Realty Associates, Inc. v. Fireman’s Fund Ins. Co., 901 N.Y.S.2d 657, 659 (2nd Dept. 2010). ↩

24. Mangano v. Am. Stock Exch., Inc., 651 N.Y.S.2d 494, 495 (1st Dept. 1996). ↩

25. Trapani v. 10 Arial Way Associates, 755 N.Y.S.2d 396 (2nd Dept. 2003). ↩

26. Chipotle, 158 N.Y.S.3d at 205. ↩

27. Lexington Ins. Co. v. Kiska Dev. Group LLC, 122 N.Y.S.3d 590, 592 (1st Dept. 2020). ↩

28. 77 Water St., Inc. v. JTC Painting & Decorating Corp., 50 N.Y.S.3d 471, 475 (2nd Dept. 2017). ↩

29. Ramcharan v. Beach 20th Realty, LLC, 942 N.Y.S.2d 593, 597 (2nd Dept. 2012). ↩

30. Lexington Ins. Co. v. Kiska Dev. Group LLC, 122 N.Y.S.3d 590, 592 (1st Dept. 2020). ↩

31. United Rentals (N.A.), Inc. v. Conti Enterprises, Inc., 293 F. Supp. 3d 447, 456 (S.D.N.Y. 2018) (applying NY law). ↩

32. Court Tobacco Stores, Inc. v. Great Eastern Insurance Company, 43 A.D.2d 561 (3rd Dept. 1973). ↩

33. State v. Ins. Co. of N.A., 333 N.Y.S.2d 486 (3d Dept. 1972). ↩

34. Stoncor Group, Inc. v. Peerless Ins. Co., 322 F. Supp. 3d 505, 508 (S.D.N.Y. 2018). ↩

35. Stellar Mech. Services of New York, Inc. v. Merchants Ins. of New Hampshire, 903 N.Y.S.2d 471, 475 (2d Dept. 2010). ↩

36. N.Y. Cas. Ins. Co. v. Shaker Pine, 262 A.D.2d 735, 736 (3rd Dept. 1999). ↩

37. Cheperuk v. Liberty Mutual Fire Insurance Company, 263 A.D.2d 748 (3d Dept. 1999). ↩

38. 137 Broadway Associates, LLC v. 602 W. 137th Deli Corp., 975 N.Y.S.2d 710 (N.Y. Sup. Ct. 2013). ↩

Appraisals for Partially Covered Insurance Claims

September 15, 2026, by Aaron Jacob, Esq.

When your insurance claim is covered under your policy, but you and your insurer disagree on the size/extent of the loss, the appraisal process is an effective way to resolve the dispute without going to court. However, when a loss is only partially covered, some insurers may try to avoid the appraisal process on the parts of the loss that are otherwise covered and ripe for appraisal. New York courts have provided useful examples to help distinguish when appraisal is appropriate or premature for these types of claims. If you received a denial letter or had your demand for an appriasal refused, send us the letter for a free review & consultation. 

Appraisal Overview

  • Appraisal is a dispute resolution process designed to give policyholders and insurers a neutral way to evaluate and determine the scope of a loss and the extent of damages. In the property insurance context, appraisal is typically used in first-party claims, e.g., claims submitted directly to one’s own insurer for a loss of one’s own property or for related damage.
  • Issues that can be resolved through Appraisal: The appraisal process can resolve a wide range of issues, including the scope of damage to real or personal property, the period of restoration, replacement cost value of property, actual cash value of property, demolition costs, the extent of a business interruption loss1, code-upgrade costs, rental income loss, mitigation costs, additional living expenses2, etc. In short, appraisal is an appropriate tool to resolve any dispute between an insurer and a policyholder over the “dollar value of the insurer’s liability” for a covered loss.3 In New York, this can include the value of loss, or the scope of a loss.4
  • Valuation vs. Coverage: Appraisals are strictly used to determine the amount or extent of a loss, but they cannot determine whether the underlying claim is covered under your policy in the first place. However, New York case law sometimes has allowed appraisal panels to untangle factual causation questions directly tied to the specific scope of damage.
  • Triggering the Clause: Either party can demand an appraisal if there is an unresolved disagreement over the extent of a loss, repair costs, or property values. The demand must usually be made in writing, and the steps are outlined in standard New York fire, property, and auto policies.
  • Selecting Appraisers: Both you and the insurance company hire and pay for your own independent, competent appraiser. The two appraisers then select a third neutral umpire. The three-person panel then evaluates the loss and determines a value.
  • The Appraisal Award: So long as the panel stayed within the scope of what it was asked to decide, an appraisal award is binding on both a policyholder and the insurer. A court will very rarely modify or vacate the award unless there is a showing of “fraud, bias, or bad faith.”5 This standard has been applied consistently and is a difficult burden to prove.

How Appraisal Works

Triggering a Demand

How to trigger the appraisal process is outlined in your insurance policy and in state law. New York, for example, has codified the appraisal process in Insurance Law § 3408.6 This statute governs the umpire-selection procedure and lets either party apply to court to compel appraisal when the amount of a loss is disputed.

The process almost always requires a written demand, which can be made by either the policyholder or the insurer. After a demand is made, each party selects its own appraiser, and the two appraisers then select a third, neutral and disinterested umpire. The three-person panel “determine[s] the actual cash value, the replacement cost, the extent of the loss or damage and the amount of the loss or damage…”7

Timeliness: Don’t Wait Too Long

The right to demand an appraisal isn’t unlimited in time. Under New York law, it must be exercised within a reasonable period, and what counts as “reasonable” depends on the facts of the case.8 A party can waive its right to an appraisal if it waits too long to demand one. Insurers often claim that an insured waited too long after a loss to demand an appraisal. Another risk of waiting, and another common excuse used by an insurer, is that the damaged property was removed, destroyed, or repaired before it can be inspected, and that appraisal is no longer practical.9

That said, courts have been reluctant to find an appraisal demand untimely just because some repairs had already occurred, particularly where the insurer suffered no real “prejudice.” For example, even a late demand can be proper where an insurer had early notice of the loss and the insurer had an opportunity to inspect and photograph the property shortly after the loss.10 A demand can even be made after litigation has already begun, with courts assessing reasonableness on a case-by-case basis rather than applying a hard cutoff.11 Therefore, a mere delay, standing alone, will not waive the right to appraisal, absent actual prejudice to the insurer.12

The Line Between Valuation and Coverage

Before an insurer will pay for any claim, the loss must be covered under that policy of insurance. Coverage issues are when there is a question or a dispute on whether a given loss is covered under the policy in the first place.

While appraisal is a powerful tool for resolving disputes over the value of a loss, the procedure is only proper when a loss is covered under a policy of insurance. The procedure is not available when there is a genuine question about coverage for the loss itself. That’s because the extent or valuation of damage is a factual question appraisers can decide, while coverage is a legal question that usually requires a court or arbitration panel to resolve. This distinction is made clear in New York Insurance Law § 3408(c).13 So, if a coverage dispute exists for a loss, it generally must be resolved before the loss can go to appraisal.14

Entire Claim Denial

An example of an outright denial and a coverage dispute over an entire loss can be seen in Kawa v. Nationwide Mutual Fire Insurance Co.,15 a case where there was a coverage dispute over what caused the damage to the aluminum siding of an insured’s house. In Kawa, a homeowner’s aluminum siding was damaged after a windstorm hit the property. The homeowner demanded an appraisal to determine how much repair work was needed for aluminum siding. However, the insurer took the position that the damage to the siding was not caused by the windstorm at all, but rather by age, wear and tear, and prior improper maintenance, all excluded causes of loss under that policy.

The Court in Kawa held that because the insurer was disputing whether the storm caused the loss in the first place (i.e., a coverage issue), and not simply how much it would cost to fix the damage from the storm (an issue for appraisal), the dispute went to liability itself, and the appraisal clause didn’t apply until the issue of coverage was resolved.

Notably, Kawa involved a dispute over what caused the entire loss, so appraisal was not appropriate. As discussed below, Kawa is distinguishable from cases where coverage issues exist on only part of a loss or cases where the insurer only claims that there are coverage issues.16

Partial Claim Denials & Pretend Coverage Disputes

The distinction between claims that are ripe for appraisal and those that are not gets murkier still when a loss involves both covered and potentially uncovered damage. Under New York law, when a claim contains both covered and potentially uncovered elements, appraisal generally remains appropriate for the covered portion of the claim. Insurance companies, however, will often try to blur this distinction to refuse or delay appraisal, even where appraisal is otherwise proper for the covered part of a claim. New York courts have repeatedly pushed back on that tactic.

Pottenburgh v. Dryden Mutual Ins. Co.: Claimed Coverage Issues

In Pottenburgh, a homeowner returned from a weekend trip to find the inside and outside of the house spray-painted with vulgarities. He reported the loss to his insurer, and the insurer inspected and photographed the damage within weeks. The homeowner’s public adjuster valued the loss at roughly $81,870 while the insurer’s own estimate came in at about $37,986.17

The homeowner demanded an appraisal to resolve the difference between the two estimates. The insurer refused to participate in appraisal, arguing the dispute wasn’t really about the amount of the loss, but rather about coverage. In this regard, the insurer claimed that the homeowner’s estimate reportedly included items the insurer said weren’t vandalized at all: a fireplace, garage siding, a bathroom, and portions of the plumbing and electrical systems. The homeowner countered that these items were included in the estimate not because they were independently damaged by the vandalism itself, but because properly repairing the indisputably vandalized portions of the house required repairing/replacing these other items too. For example, the homeowner argued that replacing the fireplace was necessary because an exact match for its damaged glass doors couldn’t be found, or that re-siding an entire wall was necessary because replacement siding couldn’t be matched to the weathered, undamaged siding beside it.

The Pottenburgh Court sided with the homeowner. In its decision, the Court held that because the insurer had never actually denied coverage for the vandalism claim itself and never identified any policy language that the Court would need to interpret, the dispute was really about the extent of work needed to fix a loss that was indisputably covered under the policy. The Court held that this is the kind of factual question that falls “squarely within the scope of the policy’s appraisal clause.”

Rivas v. United States Automobile Association: Partially Covered Claims

Rivas,18 a 2025 Supreme Court decision, illustrates that an insurer’s partial denial does not excuse it from appraisal on the covered portions of a loss. In Rivas, a homeowner’s house was damaged when a pipe froze and burst. The insured submitted a claim for approximately $187,000, covering repairs to the bathroom, closets, stairs, bedrooms, and floors, as well as personal property and living expenses. The insurer offered only about $11,000 and issued a partial denial limited to damage to the stairway carpet, a small piece of the overall claim.

The insured demanded appraisal for the covered damage (i.e., everything but the stairway carpet), but the insurer refused, pointing to its partial denial letter. The Rivas Court correctly sided with the policyholder and compelled the insurer to participate in appraisal, noting that the appraisal demand excluded the stairway carpet (the one item with a genuine coverage dispute) and incorporated only the undisputed, covered portions of the loss, which made up the bulk of the claim.

Louati v. State Farm Fire & Casualty Co.: Concurrent Live Coverage Issues

The 2018 decision in Louati19 is a case which shows that appraisal can remain available even alongside a live coverage dispute. There, a policyholder suffered water damage to their property, and the parties disagreed over whether the damage was caused by a burst pipe (a covered cause of loss) or by another, excluded cause. They also disagreed on whether it was necessary to re-tile the entire first floor when the water loss had directly affected only the bathroom.

The policyholder sought appraisal; the insurer opposed it until the causation issue of the loss could be resolved. The First Department agreed that while the issue of causation needed to be resolved first, the separate question of “whether it was necessary to re-tile the entire first floor” presented “factual questions that are properly decided in an appraisal.”

Laxminarayan Lodging v. First Specialty Ins. Corp.: Dressed Up Valuation Dispute as Coverage

A 2023 decision from the SDNY shows just how far some insurers will go to dress up a valuation dispute as a coverage dispute. In Laxminarayan Lodging, LLC v. First Specialty Insurance Corp., the insurer identified six supposed “coverage issues” standing in the way of appraisal: (1) whether physical loss occurred during the policy period, (2) whether the loss was a “prior loss,” (3) whether a wear-and-tear exclusion applied, (4) whether the roof’s age limited any recovery to actual cash value, (5) whether a cosmetic-damage exclusion barred coverage, and (6) whether the roof’s age barred recovery altogether.20

The court wasn’t persuaded. The Court held that because the insurer had already conceded partial coverage, the first issue wasn’t a live dispute at all. Additionally, none of the remaining five actually required the court to interpret any policy language, because the parties agreed on what the exclusions meant and on how old the roofs were. Rather, the policyholder and the insurer’s actual disagreement was which storm caused which damage, and how much that damage was worth. That, the court explained, is a causation dispute, and “apportioning damage causation” is “essentially a factual question” for an appraisal panel, not a legal one for the court.21

What You Need to Compel Appraisal in Court

If your insurer refuses to participate in a properly demanded appraisal, New York courts have identified what a policyholder generally needs to compel the insurer to participate: (1) a policy that contains an appraisal provision; (2) damage to property covered by that policy; (3) submission of a claim arising from the loss; (4) a genuine dispute between the parties over the value of the damages; and (5) a demand for appraisal that the insurer has refused.22

Notably, a policyholder does not need to itemize every specific area of damage underlying the disagreement to get the appraisal process started. Neither the applicable statute, case law, nor the required policy language requires that level of detail up front. Moreover, courts have treated an insurer’s own claims-handling conduct, such as making a partial payment offer during adjustment, as evidence that the real dispute is about amount, not coverage.23

However, greater detail may be recommended in claims where there are genuine issues of coverage on part of a claim. In those cases, your demand should specify that the appraisal is only demanded on the covered portions of the claim and not for the parts of the claim that have coverage issues.

* * *

New Jersey Considerations

In New Jersey, like in New York, the appraisal process is a helpful tool that can be used to resolve disputes between an insured and its insurer in claims for property loss. Briefly,

  • New Jersey law requires that all fire insurance policies contain the same or a more favorable appraisal provision that is outlined in N.J. Stat. Ann. § 17:36-5.20. The appraisal process in New Jersey has many of the same rules and restrictions as New York’s appraisal process but also differs in some places.
  • The mechanics of the appraisal process in New Jersey are similar to the process in New York. In New Jersey, after an appraisal demand is made in writing, each party selects their own appraiser, and then the two selected appraisers select a third neutral umpire. The umpire then hears both appraisers and reconciles the differences as they see fit.24
  • Under New Jersey law, similar to New York (but not identical), appraisal can only be used to resolve a dispute as to the amount of a loss but cannot be used to make legal determinations such as coverage issues or causation.25
  • Key Difference in New Jersey: New Jersey courts26 have held that the appraisal process “was not intended to resolve disputes as to the extent of damage, the scope of work required, or the cause of the damage, but rather, only for the amount of the loss.” New Jersey courts therefore differ from New York in that the former have held that “causation” (a legal issue) includes the “extent of damage sustained” from a loss.27
    • Stated another way, in New Jersey, the question of what portion of the damage to an insured’s property was caused by a covered cause of loss is ultimately a coverage issue and not appropriately decided during appraisal.28 In New Jersey, appraisal is only appropriate where “there is no dispute as to the extent of damage or the scope of work required.”
  • In New Jersey, ongoing coverage issues on part of a claim, or even the entire claim, do not prevent an appraisal from going forward, nor do they preclude either party from invoking the appraisal process.29

* * *

Aboulafia Law Firm LLC works exclusively on behalf of policyholders and has decades of experience fighting insurance companies. Whether you are dealing with a residential or commercial property claim, we are ready to help you. If you received a denial letter or had your demand for an appriasal denied, send us the letter for a free review. Don’t navigate the complex claims process alone. 

The opinions expressed are those of the author(s) and do not necessarily reflect the views of the firm, its clients, or any of its or their respective affiliates. This article is for general information purposes and is not intended to be and should not be taken as legal advice.


Footnotes

1. e.g., loss of profit that resulted from another event. ↩

2. See Olson v. E. Mut. Ins. Co., 41 N.Y.S.3d 658, 659 (N.Y. Sup. Ct. 2016) (personal property); Lyden v. Fazio Storage Warehouse Co., 143 N.Y.S.2d 460 (Sup. Ct. 1955) (same); Ram Krishana Inc. d/b/a Motel 6 Sulphur v. Mt. Hawley Insurance Co., 2025 WL 371016, at *3 (S.D.N.Y. 2025) (NY law) (mitigation costs); Woodworth v. Erie Ins. Co., 743 F. Supp. 2d 201, 218 (W.D.N.Y. 2010), on reconsideration in part, 2011 WL 98494 (W.D.N.Y. 2011) (additional living expenses); Duane Reade, Inc. v. St. Paul Fire & Marine Ins. Co., 279 F. Supp. 2d 235, 241–42 (S.D.N.Y. 2003), aff’d as modified, 411 F.3d 384, 399 (2d Cir. 2005) (duration of a business-interruption restoration period, once defined, is a valuation matter). ↩

3. See Schmid v. Allstate Ins. Co., 2017 WL 6994547, at *6 (S.D.N.Y. 2017) citing Zarour v. Pac. Indem. Co., 113 F. Supp. 3d 711, 715 (S.D.N.Y. 2015) (NY law). ↩

4. Pottenburgh v. Dryden Mut. Ins. Co., 55 Misc. 3d 775, 776–778, 48 N.Y.S.3d 885, 886–888 (N.Y. Sup. Ct. 2017). New York differs from New Jersey in this respect. In New Jersey, only value of a loss is appropriate for appraisal, while scope of a loss is not. See, German Auto. of Tinton Falls, Inc. v. Harleysville Ins. Co. of N.J., No. A-2571-13T3, 2014 N.J. Super. Unpub. LEXIS 1952, at *6 (Super. Ct. App. Div. July 29, 2014). ↩

5. Forbes v. Cendant Corp., 205 F.3d 1322 (2d Cir. 2000); Coral Crystal, LLC v. Fed. Ins. Co., No. 17-CV-1007 (LTS)(BCM), 2020 WL 5350306, at *5 (S.D.N.Y. Sept. 3, 2020). ↩

6. See also, Ins. Law § 3404(e); § 3404(g). ↩

7. Ins. Law § 3408(c); see also, Louati v. State Farm Fire & Cas. Co., 161 A.D.3d 701, 702 (1st Dep’t 2018). ↩

8. Chainless Cycle Mfg. Co. v. Security Ins. Co., 169 N.Y. 304, 310 (1901); Peck v. Planet Ins. Co., No. 93-4961 (MBM), 1994 WL 381544, at *3 (S.D.N.Y. July 21, 1994). ↩

9. Chainless Cycle Mfg. Co., 169 N.Y. at 312; Uhrig v. Williamsburgh City Fire Ins. Co., 101 N.Y. 362, 366 (1886); see also Richardson v. Merrimack Mut. Fire Ins. Co., No. 98-5967 (JFK), 2000 WL 297171, at *5 (S.D.N.Y. Mar. 21, 2000). ↩

10. Pottenburgh v. Dryden Mut. Ins. Co., 55 Misc. 3d 775, 48 N.Y.S.3d 885 (N.Y. Sup. Ct. 2017). ↩

11. Amerex Grp., Inc. v. Lexington Ins. Co., 678 F.3d 193, 200 (2d Cir. 2012). ↩

12. Zarour v. Pac. Indem. Co., 113 F. Supp. 3d 711, 716 (S.D.N.Y. 2015). ↩

13. The last sentence of Ins. Law § 3408(c) states that “Notwithstanding the provisions of this subsection, an appraisal shall not determine whether the policy actually provides coverage for any portion of the claimed loss or damage.” ↩

14. Penn Central Corp. v. Consol. Rail Corp., 56 N.Y.2d 120, 127 (1982); In re Delmar Box Co., 309 N.Y. 60, 63 (1955); Lee v. Hamilton, 251 N.Y. 230, 234 (1929); Maimes v. Automobile Ins. Co., 112 Misc. 656, 657, 183 N.Y.S. 690, 691 (Sup. Ct., Monroe Cnty. 1920), aff’d, 196 A.D. 921, 187 N.Y.S. 943 (1921). ↩

15. Kawa v. Nationwide Mut. Fire Ins. Co., 174 Misc. 2d 407, 408, 664 N.Y.S.2d 430, 431 (Sup. Ct. 1997). ↩

16. Pottenburgh, 55 Misc. 3d 775, 778 (N.Y. Sup. Ct. 2017) (distinguishing Kawa). ↩

17. Pottenburgh v. Dryden Mut. Ins. Co., 55 Misc. 3d 775, 776–778, 48 N.Y.S.3d 885, 886–888 (N.Y. Sup. Ct. 2017). ↩

18. Leonel Rivas v. United States Automobile Association, No. 036345/2024 (N.Y. Sup. Ct., Rockland Cnty. Aug. 11, 2025). This case was successfully litigated by the author. ↩

19. Louati v. State Farm Fire & Cas. Co., 161 A.D.3d 701, 702, 77 N.Y.S.3d 51, 52 (1st Dep’t 2018). ↩

20. Laxminarayan Lodging, LLC v. First Specialty Ins. Corp., 2023 WL 3382867, at *3–4 (S.D.N.Y. May 11, 2023) citing Milligan v. CCC Info. Servs., Inc., 920 F.3d 146, 154 (2d Cir. 2019). ↩

21. Zarour, 113 F. Supp. 3d at 715–16 citing Amerex, 678 F.3d at 206. ↩

22. Pottenburgh, 55 Misc. 3d at 777; Hyman v. State Farm Fire & Cas. Co., No. 154703/2016, 2016 WL 5630716 (Sup. Ct., N.Y. Cnty. 2016); Ins. Law § 3408. ↩

23. Olson, 54 Misc. 3d at 579, 41 N.Y.S.3d at 660. ↩

24. See DC Plastic Prods. Corp. v. Westchester Surplus Lines Ins. Co., 2022 WL 3083720, at *5 (D.N.J. Aug. 3, 2022). ↩

25. See Rastelli Bros. v. Netherlands Ins. Co., 68 F. Supp. 2d 440, 446 (D.N.J. 1999) citing Elberon Bathing Co., Inc. v. Ambassador Ins. Co., Inc., 77 N.J. 1, 15, 389 A.2d 439 (NJ 1978). ↩

26. Interpreting the statutory language “If we and you disagree on the amount of loss, either may make written demand for an appraisal of the loss.” N.J. Stat. Ann. § 17:36-5.20. ↩

27. Fox v. State Farm Fire & Cas. Co., 2021 WL 4398740, at *7 (D.N.J. Sept. 24, 2021) (insurer argued that the insured’s estimates for repairs included items that were not damaged during the occurrence); Campbell v. N.J. Ins. Underwriting Ass’n, 2014 WL 10679851, at *3 (N.J. Super. Ct. L. Div. Sep. 11, 2014) (“a significant dispute … as to what portion of the damage to plaintiffs’ property was caused by a peril (i.e., wind)”); see also, German Auto. of Tinton Falls, Inc. v. Harleysville Ins. Co. of N.J., No. A-2571-13T3, 2014 N.J. Super. Unpub. LEXIS 1952, at *6 (Super. Ct. App. Div. July 29, 2014) (holding that the dispute concerned more than the value of the loss, but also the extent of the damage sustained). ↩

28. Id. ↩

29. See DC Plastic Prods. Corp. v. Westchester Surplus Lines Ins. Co., No. CV 17-13092 (SRC), 2021 WL 2018918, at *2 (D.N.J. May 19, 2021) (holding that “even if outstanding liability issues exist, there is no reason to delay determining the amount of the loss in the meantime”); see also, Ward v. Merrimack Mut. Fire Ins. Co., 332 N.J. Super. 515, 528, 753 A.2d 1214, 1221 (App. Div. 2000) citing Hala Cleaners, Inc. v. Sussex Mut. Ins. Co., 115 N.J. Super. 11, 12–13, 277 A.2d 897 (Ch. Div. 1971). ↩