
September 2026, by Aaron Jacob, Esq.
As discussed in Part 1, additional insureds are parties who are entitled to insurance coverage under someone else’s (the “named insured”) policy of insurance, and under New York law, they are entitled to the same type of coverage under the policy as the named insured.1
If a claim is filed against you, there are three things needed before you can enjoy full protection as an additional insured:
(1) that you qualify as an additional insured;
(2) that the duty to defend has been triggered; and
(3) that, if the claimant is ultimately successful on their claims, the duty to indemnify has been triggered.
Part 1 addressed the first requirement, i.e., proving that you qualify as an additional insured, including how to analyze the additional insured endorsement and its schedule, the level of contract formality the endorsement requires, privity of contract, and misnomer issues.
Once you have established additional insured status, the analysis turns to whether the underlying claim is covered under the named insured’s policy, i.e., whether the insurer has an obligation to provide coverage for the additional insured for the claim.
In this regard, there are two distinct duties of an insurance company with respect to providing additional insured coverage: (1) the duty to defend, and (2) the duty to indemnify. The former is an insurance company’s duty to hire attorneys to defend the additional insured in the lawsuit, while the latter is an insurance company’s duty to actually pay for the claimed injury, should the claimant be successful in the lawsuit.
This part addresses both duties, as well as the policy conditions and exclusions that can stop coverage for an additional insured for an event, and the requirements that Insurance Law § 3420(d) imposes on an insurer when it responds to a tender or denies coverage.
I. The Duty to Defend
It is well settled under New York law that an insurance company’s duty to defend is “exceedingly broad”2 and that “additional insureds are entitled to the same type of coverage under the policy as the named insured.”3 The duty to defend is broader than an insurer’s duty to indemnify.4
When applied to an additional insured, the scope of an insurer’s duty to provide additional insured coverage depends on the language of the endorsement that qualified that party to additional insured status. The following two policy forms are examples of endorsements that convey additional insured status and quantify the scope of such status:
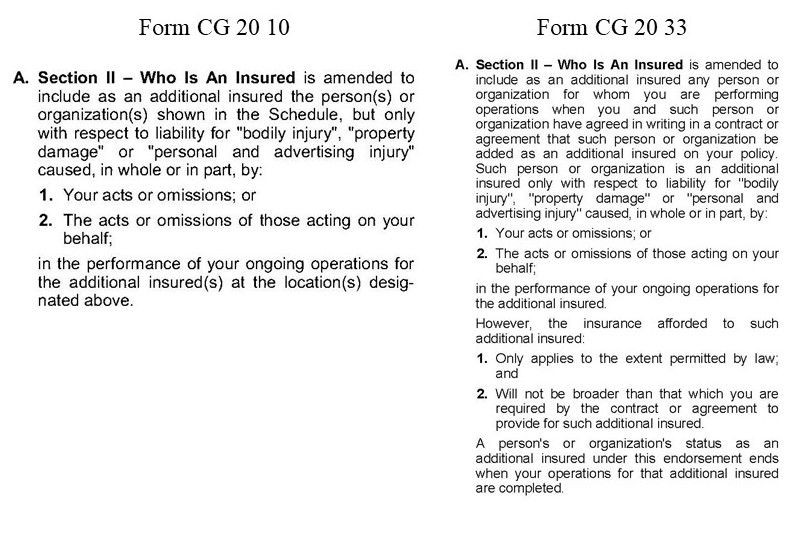
As seen, these above common additional insured endorsements provide that there is additional insured coverage for liability “caused, in whole or in part,” by the “acts or omissions” of the named insured.5 This language was analyzed in Burlington Ins. Co. v NYC Tr. Auth., where the Court of Appeals held that “caused, in whole or in part” means “proximate cause.”6
Critically, the Burlington standard is applicable to whether an insurer has a duty to indemnify its insureds, but this standard does not have to be met (or proven) before the duty to defend is triggered. This is because the duty to defend an insured is a much lower bar, and so it is triggered by a claim having only a reasonable possibility of meeting the Burlington standard (i.e., that there is a reasonable possibility that the named insured was a proximate cause of the claimant’s injury).7
Therefore, an additional insured does not need to prove the named insured was an actual proximate cause of the claim/injury to be entitled to a defense, as that determination usually waits for a court or jury. Only the possibility of that finding is required to trigger a duty to defend.8 Once triggered, an insurer must defend the additional insured no matter how groundless, false or baseless the suit may be.9
The possibility of coverage, and therefore, the duty to defend, can be triggered in multiple ways, including even when a complaint doesn’t contain any allegations that the named insured was negligent, just so long as the insurer has knowledge of facts that establish a reasonable possibility of coverage.10 Some examples of where the duty to defend is triggered include:
(1) where the allegations of a complaint directly “suggest … a reasonable possibility of coverage” (e.g., the claimant says that they were injured while working for the named insured, or while working for a subcontractor of a named insured11);
(2) extrinsic evidence outside the complaint suggests the possibility of coverage (e.g., a contract provided to the insurer showing that the named insured was working on site on the day of injury); or
(3) even a third-party complaint that was filed by the additional insured, can trigger an insurer’s duty to defend12 (e.g., the additional insured sues the named insured for indemnification for the claimed injury).
The Burlington standard is commonly weaponized by insurers to avoid providing any coverage to its additional insureds, including providing a defense. This is because once an insurer steps in to defend its additional insured, it cannot withdraw from that defense without a court order13. A common excuse found in tender rejection letters is that the additional insured is not entitled to coverage because, for example, there is no proof that the claim/injury was caused by, in whole or in part, the acts or omissions of the named insured. This is a transparent misuse of the Burlington standard and should be challenged by any party seeking additional insured coverage.
Therefore, when tendering to an insurance company, or analyzing an insurer’s response to the tender, review and provide every available fact that would trigger the duty to defend, including:
(a) the pleadings (the named insured need not even be a party — for example, where the plaintiff is the named insured’s employee);
(b) discovery materials (deposition testimony, bills of particulars, etc.);
(c) third-party complaints — including one filed by the party seeking additional insured coverage itself; and
(d) known facts outside the four corners of the complaint, which can help trigger the duty to defend (e.g., a contract showing that the named insured was working on site at the time of the injury); and
(e) importantly, an insurer cannot rely on outside information to escape a defense obligation that the allegations otherwise trigger.14
Key takeaway: If an insurer disclaims based on the complaint alone, check whether discovery, a third-party complaint, or facts you already know about the loss would independently support the reasonable-possibility standard and put the insurer on notice of those facts in writing.
Because an additional insured’s right to a defense is based upon the reasonable possibility that the named insured was a proximate cause of the claimed injury, an insurer’s duty to defend an additional insured will end when the named insured is dismissed from the case, i.e., if and when the named insured is found not to have any liability for the alleged injury.15 However, the dismissal of the named insured (via summary judgment, directed verdict, or otherwise) cannot be used to retroactively alleviate an insurer’s duty to defend an additional insured.16 Therefore, even in cases where the named insured is eventually dismissed from an action, because the insurer would still have owed a duty to defend the additional insured up until the point of dismissal, an insurer would still be obligated to share or reimburse the additional insured’s defense costs up until the date of the named insured’s dismissal.17
Relatedly, in the event of a breach of the insurer’s duty to defend an additional insured, the additional insured’s damages are the expenses reasonably incurred by it in defending the action from the date of the insurer’s refusal to do so.18
II. The Duty to Indemnify
The partner of the duty to defend is the duty to indemnify. Indemnification of a claim means that the insurer will have to pay for the liability of its insureds, if the claimant is successful in the lawsuit. As discussed above, this means that if the additional insured endorsement uses the language “caused, in whole or in part”, then under the Burlington standard, the duty to indemnify will trigger where the named insured was at least a proximate cause of the liability. Proximate cause does not mean that the named insured was 100% liable for the injury, but only that the named insured was as little as 1% of the proximate cause of the injury.19 However, because proximate cause is a legal determination, it ultimately requires a judicial finding.
Notably, additional insured coverage may even include injuries that were caused by affirmative negligence on the part of the additional insured, so long as the named insured was a proximate cause of that injury.20 Moreover, in cases where the named insured is the employer of the injured claimant, the claimant’s own negligence can be imputed onto the named insured based on respondeat superior principles.21
There are some policy forms that use a different trigger than the Burlington language. For example, the term “arising out of”, as seen in the below form, is a broader, alternative trigger. “Arising out of” means “originating from, incident to, or having connection with.”22 This broader term requires only some causal relationship between the injury and the insured risk to trigger an insurer’s duties. 23
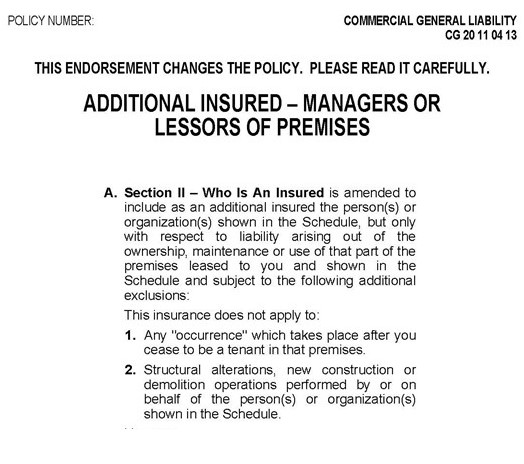
Under the “arising out of” language, the focus of the indemnification trigger is on the general nature of the operation during which the injury occurred, and you do not need to wait for a judicial determination of liability to trigger indemnity under this standard24. For example, where a claimant was injured while in the context of their employment with the named insured, a form with the language “arising out of” will be triggered regardless of whether the named insured was at fault.25
However, even this broader language will not trigger in every circumstance. Two examples where courts found no “arising out of” connection are as follows:
• A subcontractor had finished installing stairs and left the site; the general contractor conceded the staircase was merely the situs of the accident.26
• A bodily injury occurring outside the leased premises did not arise out of the named insured’s performance operations at the premises.27
III. Conditions and Exclusions
Even when a claim otherwise triggers additional insured coverage, certain policy terms, conditions, or exclusions can stop coverage for an event. Some of these conditions, terms, or exclusions may be imposed on the named insured, and some on the additional insured.
Conditions
Conditions in insurance policies can be express or implied.28 Express conditions are those agreed to and imposed by the parties themselves. In an insurance context, express conditions “must be literally complied with before a party to the contract may recover.” If a condition is a “condition precedent”, that condition must occur before an insurer has any obligation to perform its duties. More so, if there is a “condition precedent”, an insurer only needs to show that the condition was not met to avoid coverage, it does not need to show that it was prejudiced by the insured’s failure to meet that condition. A condition precedent usually but not always states that it is a condition precedent.
A common policy condition is that an insured must notify the insurer as soon as possible after it discovers or is notified of a claim, or that an insured must cooperate with the insurer. An example of a condition precedent is where a named insured must require its subcontractors to name it as an additional insured in their policies (and that the policy states that such requirement is a condition precedent).
That said, a named insured’s breach of a policy condition — including a condition precedent, such as late notice or lack of cooperation — is not grounds for disclaiming coverage to an additional insured.29 This means that if the named insured breached a policy condition by, for example, failing to notify the insurer of a claim until very late, an additional insured would still be entitled to coverage under that policy, even though the named insured was excluded from coverage for its failure to satisfy a condition.
Therefore, an insurer cannot point to the named insured’s own missteps in handling the claim to deny your separate coverage. (A breach of a condition by the additional insured itself is a different matter and can be grounds for denial.)
That said, some acts of the named insured may still invalidate coverage for the additional insured. Usually, these types of breaches invalidate the entire policy. An example of this would be if the named insured had a material misrepresentation in the application of the policy. If the insurer can prove this, and that they were prejudiced by that misrepresentation, they may be allowed to void or rescind the entire policy, ab initio, or stated otherwise, make it as if the policy was never issued in the first place.
If a policy is voided, ab initio, there would not be any additional insured coverage because there was no policy in the first place. That is because “additional insureds, by definition, must exist in addition to something; namely, the named insureds in a valid existing policy.”30
However, once a claim has been made, an insurer cannot rescind or void a policy by notice (to the named insured), because the rights of the insureds and additional insureds have already accrued.31 Therefore, once a claim has been made, an insurer would need a judicial determination before it would be allowed to rescind a policy.32
Exclusions
An exclusion is a policy term that seeks to exclude coverage for an otherwise covered event. These differ from conditions in that conditions can apply before coverage may be applied, while exclusions only apply after coverage for a claim is triggered. Exclusions can apply to additional insureds.
Whether an exclusion applies to an additional insured depends entirely on the policy’s wording, usually, whether the policy uses the language “the insured” or “any insured.”
• “The insured” limits a condition or exclusion to the particular insured it describes, or to the particular insured seeking coverage;
• “Any insured” (or “an insured”) binds all insureds to the consequences of any one insured’s act;
• The “named insured” is limited only to the named insured on the policy declarations.
These terms are commonly found in exclusions for an employee injury. For example, if an exclusion states that it applies for injury to an employee of the insured, the exclusion only bars coverage for the specific insured who actually employed the plaintiff, but it will not apply for an additional insured who was not the employer. If the same exclusion is written for an employee of “any insured”, then the exclusion bars coverage for all insureds, named and additional alike, if any of them employed the injured person.33 Therefore, some exclusions that would apply to one insured, may not apply to another.
Key takeaway: Always read the exact article of the exclusion the insurer is relying on. If it says “the insured” and the excluded conduct or relationship belongs only to the named insured, that exclusion should not reach you.
IV. Insurance Law § 3420(d) & Denial Letters
Insurance Law §3420(d) is a strong tool for any insured. This statute applies to any liability policy that provides coverage with respect to a claim arising out of the death or bodily injury of any person. This statute does not apply, however, to claims not for bodily injury/death, like for example, a claim for property damage or business interruption losses.
This provision outlines the requirements of an insurer’s response to a claim (arising out of bodily injury), such as a tender response, denial letter, reservation of rights, etc. Critically, “failure to comply with section 3420(d) precludes denial of coverage based on a policy exclusion.”34 So an insurer’s procedural defect under this provision can invalidate its entire position and waive its right to rely on policy exclusions.
• The basic requirement of Section 3420(d)(2) is that an insurer shall give written notice as soon as is reasonably possible of any denial letter to the insured and the injured person or any other claimant.
The determination of what is “as soon as reasonably possible” is generally fact specific, as not all the grounds for an exclusion will be available at the outset of a claim. Timeliness of insurer’s disclaimer of liability is measured from time when insurer first learns of grounds for disclaimer or denial of coverage35.
That said, “where the sole ground upon which the disclaimer is based is obvious from the face of the notice of claim and accompanying complaint, a delay of even 30 days has been held to be unreasonable.”36 If the grounds for a disclaimer are obvious, an insurer will have to provide an acceptable excuse for its delay, or else it will waive its right to deny the claim37.
An example of this is where an insurer denies coverage to a named insured, and months later, an additional insured tenders for coverage. If the insurer denies the additional insured tender on the same grounds as it denied the named insured’s claim, any excuse for a late denial letter will be insufficient as a matter of law38 (because the grounds for its disclaimer were already obvious by virtue of its disclaimer to the named insured).
• Section 3420(d)(2) requires that a disclaimer letter include, “with a high degree of specificity,” the ground or grounds on which the disclaimer is predicated.39 If a disclaimer letter does not specify a certain ground for its denial, the insurer will waive its right to rely on that ground for excluding coverage.40
A disclaimer letter must “identify the applicable policy exclusion and set forth the factual basis for the insurer’s position that the claim fell within a policy exclusion, with sufficient specificity to satisfy the statutory mandate and purpose.”41 That said, a small misquotation or a partial omission of the policy language of an exclusion does not invalidate it automatically, so long as the letter is otherwise sufficiently specific on the exclusion’s application.42 If an insurer denies coverage on one ground, then it will have waived all other grounds for denial (that were available at that time).
• Section 3420(d)(2) applies to additional insureds.43 Under New York law, additional insureds are entitled to the same protections as a named insured, including timely notice of disclaimer.44
• Section 3420(d)(2) requires the insurer to send disclaimer notice directly to the additional insured (or its counsel), and failure to do so precludes the insurer from disclaiming based on an exclusion.45 A letter sent only to the additional insured’s own insurer does not satisfy § 3420(d)(2).46
• If an additional insured receives the same copy of the disclaimer that was sent to the named insured, this letter can satisfy § 3420 — but only if that letter specifically addresses coverage for the additional insured (e.g., “therefore, there is no coverage available under the Policy for this claim for any party, including any additional insureds”).47 If a disclaimer only addresses the named insured’s own coverage, the disclaimer letter will not apply to the additional insured for 3420(d) purposes. For example, if the denial letter only addresses a late notice breach by the named insured, or an employee exclusion that only applies to the named insured, the letter will not satisfy the 3420(d) disclaimer requirements to an additional insured.48
• A reservation of rights letter does not constitute compliance with the requirements of section 3420(d).49
• 3420(d) applies whether the policy of insurance is primary or excess.50
• An insurer must still disclaim coverage as soon as reasonably possible even where the insured failed to provide timely notice of claim.51
Any failure on any of these points is an independent basis to challenge the denial, separate from the merits of coverage.
When tendering a claim on your behalf, confirm the package includes:
• Identification of who is tendering and on whose behalf;
• The named insured and the specific policy being tendered to (if available);
• The claim documentation (complaint, notice of loss, etc.);
• The contract or agreement connecting you to the named insured, matched against the endorsement’s exact requirement (contract vs. written contract vs. executed written contract, and scheduled vs. blanket basis); and
• A letter invoking the triggering language for the duty to defend with supporting facts (from the pleadings, discovery, or otherwise).
* * *
Aboulafia Law Firm LLC works exclusively on behalf of policyholders and has decades of experience fighting insurance companies. Whether you are dealing with a residential or commercial property claim, we are ready to help you. If you are seeking to obtain additional insured coverage or are dealing with a tender, don’t navigate the complex claims process alone. For assistance on your insurance claim, please contact us.
The opinions expressed are those of the author(s) and do not necessarily reflect the views of the firm, its clients, or any of its or their respective affiliates. This article is for general information purposes and is not intended to be and should not be taken as legal advice.
Aaron Jacob is a senior associate at Aboulafia Law Firm LLC. Mr. Jacob is a skilled litigation and coverage attorney and has extensive experience representing commercial and private clients involved in property damage and insurance coverage claims in complex state and federal court matters.
Mr. Jacob focuses his practice on advocating for policyholders in high-exposure property damage cases, insurance recovery claims, coverage disputes, construction-related claims, declaratory judgments, first & third-party claims, business interruption losses, indemnification, additional insured coverage, broker negligence, risk transfer, contractor/subcontractor liability, bad faith claims, contribution claims, breach of contract disputes, and general liability defense, as well as in litigating insurance coverage issues under several policy lines including homeowners, commercial liability, excess/umbrella, businessowners, cargo, freighting, and commercial auto policies.
Footnotes
1. Pecker Iron Works of N. Am., Inc. v. Travelers Ins. Co., 99 N.Y.2d 391 (2003). ↩
2. Auto. Ins. Co. of Hartford v. Cook, 7 N.Y.3d 131, 137 (2006). ↩
3. Pecker Iron Works of N. Am., Inc. v. Travelers Ins. Co., 99 N.Y.2d 391 (2003) ↩
4. Auto. Ins. Co. of Hartford v. Cook, 7 N.Y.3d at 137. ↩
5. An alternative trigger to “caused, in whole or in part,” is “arising out of”, discussed later. ↩
6. Burlington Ins. Co. v NYC Tr. Auth., 57 N.Y.S.3d 85 (2017). ↩
7. Indian Harbor Ins. Co. v. Alma Tower, LLC, 87 N.Y.S.3d 9, 10 (1st Dept. 2018) (“because there is a reasonable possibility that [the named insured] proximately caused the injury…”); Live Nation Mktg., Inc. v. Greenwich Ins. Co., 188 A.D.3d 422, 423, 135 N.Y.S.3d 87, 89 (1st Dept. 2020). ↩
8. Citizens Ins. Co. of Am. v. Am. Ins. Co., 130 N.Y.S.3d 289, 290 (1st Dept. 2020) ↩
9. Automobile Ins. Co. of Hartford v. Cook, 850 N.E.2d 1152, 1155 (2006). ↩
10. WDF Inc. v. Harleysville Ins. Co. of New York, 146 N.Y.S.3d 128 (1st Dept. 2021); Indian Harbor Ins. Co. v. Alma Tower, LLC, 87 N.Y.S.3d 9 (1st Dept. 2018) ↩
11. Exeter Bldg. Corp. v. Scottsdale Ins. Co., 913 N.Y.S.2d 733 (2d Dept. 2010) ↩
12. Automobile Ins. Co. of Hartford v. Cook, 850 N.E.2d at 1155; see also, Wesco Ins. Co. v. Hellas Glass Works Corp., 2020 NY Slip Op 06975, ¶ 1, 188 A.D.3d 621, 621, 132 N.Y.S.3d 758, 758 (App. Div. 1st Dept. 2020); One Reason Rd., LLC v. Seneca Ins. Co., Inc., 83 N.Y.S.3d 235, 238 (2nd Dept. 2018); All State Int. Demolition Inc. v. Scottsdale Ins. Co., 92 N.Y.S.3d 256, 257 (1st Dept. 2019); Indian Harbor Ins. Co. v. Alma Tower, LLC, 165 AD3d 549, 549 (1st Dept 2018); Greater New York Mut. Ins. Co. v. State Natl. Ins. Co., Inc., 120 N.Y.S.3d 578 (N.Y. Sup. Ct. 2019); Travelers Prop. Cas. Co. of Am. v. Harleysville Ins. Co. of N.Y., 128 N.Y.S.3d 154 (Sup. Ct. 2020) (rejecting an insurer’s argument that a third-party complaint cannot be relied upon to establish a duty to defend). ↩
13. Seye v. Sibbio, 821 N.Y.S.2d 473 (2d Dept. 2006) ↩
14. Fitzpatrick v. Am. Honda Motor Co., Inc., 575 N.E.2d 90 (1991). ↩
15. Monadnock Const., Inc. v. DiFama Concrete, Inc., 896 N.Y.S.2d 107, 108 (2d Dept. 2010) ↩
16. Allied World Assurance Co. (U.S.) Inc. v. Aspen Specialty Ins. Co., 139 N.Y.S.3d 816, 817 (1st Dept. 2021) ↩
17. Id.; see also, City of Niagara Falls v. Merchants Ins. Group, 824 N.Y.S.2d 841, 842–43 (4th Dept. 2006) ↩
18. Nat’l Union Fire Ins. Co. of Pittsburgh, PA v. Greenwich Ins. Co., 103 A.D.3d 473, 474, 962 N.Y.S.2d 9, 11 (1st Dept. 2013) ↩
19. Burlington Ins. Co. v NYC Tr. Auth., 57 N.Y.S.3d 85 (2017); Starr Indem. & Liab. Co. v. Excelsior Ins. Co., 516 F. Supp. 3d 337, 349 (S.D.N.Y. 2021) (NY law) ↩
20. Breeze Natl., Inc. v. Cent. Sur. Co., 96 N.Y.S.3d 56, 57 (1st Dept. 2019); E.E. Cruz & Co., Inc. v. Axis Surplus Ins. Co., 87 N.Y.S.3d 173, 175 (1st Dept. 2018). ↩
21. Guiga v. JLS Const. Co., Inc., 685 N.Y.S.2d 1, 2 (1st Dept. 1998); Mercado v. Caithness Long Island LLC, 961 N.Y.S.2d 424, 427 (1st Dept. 2013) ↩
22. Regal Constr. Corp. v National Union Fire Ins. Co. of Pittsburgh, PA, 15 NY3d 34, 38, 930 N.E.2d 259, 904 N.Y.S.2d 338 (2010) ↩
23. Id. ↩
24. Hunter Roberts Const. Group., LLC v. Arch Ins. Co., 75 AD3d 404, 408 (1st Dept. 2010) ↩
25. Id. ↩
26. Worth Const. Co., Inc. v. Admiral Ins. Co., 888 N.E.2d 1043 (2008). ↩
27. Christ the King Regl. High Sch. v. Zurich Ins. Co. of N.A., 937 N.Y.S.2d 290, 294 (2nd Dept. 2012). ↩
28. Oppenheimer & Co. v. Oppenheim, Appel, Dixon & Co., 636 N.Y.S.2d 734, 660 N.E.2d 415, 418 (1995); Seaport Park Condo. v. Greater New York Mut. Ins. Co., 828 N.Y.S.2d 381, 384 (1st Dept. 2007). ↩
29. 233 E. 17th St., LLC v. L.G.B. Dev., Inc., 913 N.Y.S.2d 110, 112 (2nd Dept. 2010). ↩
30. Admiral Ins. Co. v. Joy Contractors, Inc., 19 N.Y.3d 448, 461 (2012) ↩
31. Fed. Ins. Co. v. Kozlowski, 792 N.Y.S.2d 397, 402 (1st Dept. 2005); Kiss Const. NY, Inc. v. Rutgers Cas. Ins. Co., 877 N.Y.S.2d 253, 256 (1st Dept. 2009); Indian Harbor Ins. Co. v. Alma Tower, LLC, 87 N.Y.S.3d 9, 10 (1st Dept. 2018) ↩
32. Id. ↩
33. Moleon v. Kreisler Borg Florman Gen. Const. Co., Inc., 758 N.Y.S.2d 621, 624 (1st Dept. 2003); Sixty Sutton Corp. v. Illinois Union Ins. Co., 825 N.Y.S.2d 46, 49 (1st Dept. 2006); Soho Plaza Corp. v. Birnbaum, 969 N.Y.S.2d 96, 100 (2d Dept. 2013). ↩
34. Matter of Worcester Ins. Co. v Bettenhauser, 95 NY2d 185, 188, 734 N.E.2d 745, 712 N.Y.S.2d 433 (2000) ↩
35. Allcity Ins. Co. v Jimenez, 78 N.Y.2d 1054, 576 N.Y.S.2d 87, 581 N.E.2d 1342, (1991); Plotkin v. Republic-Franklin Ins. Co., 177 A.D.3d 790, 793-94, 113 N.Y.S.3d 133, 138 (2nd Dept. 2019) ↩
36. Gagosian Gallery, Inc. v. Eurostruct, Inc., 814 N.Y.S.2d 890 (N.Y. Sup. Ct. 2005) citing West 16th Street Tenants Corp. v. Pub. Service Mut. Ins. Co., 736 N.Y.S.2d 34 (1st Dept. 2002). ↩
37. Id., see also AIU Ins. Co. v. Veras, 942 N.Y.S.2d 532, 533 (1st Dep’t 2012); Sirius Am. Ins. Co. v. Vigo Const. Com., 852 N.Y.S.2d 176, 178 (2d Dep’t 2008) (finding 34-day delay unreasonable as a matter of law where no explanation was provided). ↩
38. Plotkin v. Republic-Franklin Ins. Co., 177 A.D.3d 790, 793-94, 113 N.Y.S.3d 133, 138 (2nd Dept. 2019) citing Stout v 1 E. 66th St. Corp., 90 A.D.3d 898, 902, 935 N.Y.S.2d 49, 54 (2nd Dept 2011) ↩
39. Gen. Accident Ins. Grp. v. Cirucci, 46 N.Y.2d 862, 414 N.Y.S.2d 512, 387 N.E.2d 223, 225 (1979). ↩
40. Id., see also Zappone v. Home Ins. Co., 55 N.Y.2d 131, 135 (1982) ↩
41. Adams v. Perry’s Place, 168 A.D.2d 932, 564 N.Y.S.2d 1019, 1019 (1990). ↩
42. Id. ↩
43. See Sierra v 4401 Sunset Park, LLC, 957 N.Y.S.2d 219 (2d Dept 2012), affd 25 N.E.3d 921 (2014); Matter of Worcester Ins. Co. v Bettenhauser, 95 NY2d 185, 188, 734 N.E.2d 745, 712 N.Y.S.2d 433 (2000). ↩
44. Id. ↩
45. Sierra v. 4401 Sunset Park, LLC, 24 N.Y.3d 514, 2 N.Y.S.3d 8 (2014). ↩
46. Id. (“The obligation imposed by the Insurance Law is to give timely notice to the mutual insureds … not to … another insurer”). ↩
47. Valiant Ins. Co. v. Utica First Ins. Co., 185 A.D.3d 435, 436 (1st Dept. 2020) ↩
48. Pofi Constr. Corp. v. Rutgers Cas. Ins. Co., 137 N.Y.S.3d 314, 315 (1st Dept. 2020); Endurance Am. Specialty Ins. Co. v. Utica First Ins. Co., 17 N.Y.S.3d 401, 403 (1st Dept. 2015). ↩
49. Zappone v. Home Ins. Co., 55 N.Y.2d 131, 135 (1982). ↩
50. Id. ↩
51. First Fin. Ins. Co. v. Jetco Contracting Corp., 801 N.E.2d 835, 837 (2003). ↩
