
September 2026, by Aaron Jacob, Esq.
Risk protection and liability transfer are of critical importance to any property owner, general contractor, lessor, licensor, or other businesses that contract with subcontractors, vendors, lessees, licensees, or other downstream entities. Most contracts and subcontracts already require the downstream party to carry insurance and name the upstream party as an “additional insured” on their insurance policy as well as contain indemnification rights. Often, you will also get a certificate of insurance from that party, purportedly showing that they procured the required coverage.
However, if a claim ever gets filed, many parties suddenly find themselves without the contracted-for protection and find that the certificate of insurance is not worth the paper it is written on. Then, the upstream party has to use its own insurance to defend them against a claim, or if they are uninsured, pay out of pocket for counsel. This is at least partly because insurers routinely look for reasons to deny additional insured requests and find opportunities to deny tenders or indemnification demands due to a handful of technicalities in contracts or policies that come up repeatedly.
Drafting the contract carefully and securing the correct policy initially alleviates many of the issues but also understanding how you can trigger additional insured coverage and/or indemnification rights, or challenge an insurer’s response after the fact, can be incredibly helpful.
An analysis of common additional insured endorsements under New York law is below, including what a party needs to prove to qualify as an additional insured, what to include in your tender, and what to require up front when drafting the contract so a future tender doesn’t run into an avoidable problem.
What Are Additional Insureds?
Additional insureds are parties who are entitled to insurance coverage under someone else’s (the “named insured”) policy of insurance. A classic example is an owner of a property requiring that they are named as an additional insured on a policy of insurance held by a contractor who is performing construction work at the owner’s property. This way, if someone is injured during construction as a result of the contractor’s work, and the injured party sues the owner, the owner can look to the contractor’s insurer for insurance coverage to defend the claims.
Under New York law, additional insureds are entitled to the same type of coverage under the policy as the named insured.1 Similarly, the standard for determining whether an additional insured is entitled to coverage for a claim is the same standard as determining whether a named insured is entitled to coverage.2
However, there are many types of policy forms and endorsements that purport to provide additional insured coverage, but they are not all equal in how easy it is to qualify for that coverage. If a claim is filed against you, there are three things needed before you can enjoy full protection as an additional insured.
(1) that you qualify as an additional insured;
(2) that the duty to defend has been triggered; and
(3) that, if the claimant is ultimately successful on their claims, the duty to indemnify has been triggered.
In New York, there are also laws that protect insureds from certain acts by an insurance company, including a late response (Ins. Law 3420(d)), discussed in Part 2 of this article. This Part 1 addresses the first requirement, i.e., proving that you qualify as an additional insured.
The Complete Tender Package
Proving you qualify as an additional insured
The burden is on the party seeking additional insured coverage to establish entitlement in the first instance.3 Because that burden falls on you, the tender should be drafted so that the insurer has no room to claim the proof was insufficient. A complete tender package should include:
(a) the identity of who is sending the tender (and on whose behalf) — you, your attorney, or your own insurer;
(b) the identity of the named insured and the policy under which additional insured coverage is sought;
(c) information about the underlying claim, with supporting documents — e.g., the summons and complaint, or a claimant’s notice of loss; and
(d) documentation connecting the named insured to the claim and to your right to additional insured status — typically the contract between you and the named insured requiring the additional insured endorsement.
Key takeaway: Before you send the tender, compare the underlying contract against the specific requirements of the additional insured endorsement itself (discussed below). A mismatch between the two is a very common reason insurers reject a tender — catching it before you send the package lets you gather better proof instead of receiving a denial. And if you are instead the party requiring this coverage from a subcontractor or vendor, this is also exactly what to fix at the drafting stage: keep the fully executed contract and the actual additional insured endorsement — not just a certificate of insurance — in the project file for the life of the project plus the statute of limitations, so this step is never the reason a future tender fails.
The Additional Insured Endorsement
The two most common issues in qualifying for additional insured coverage arise from either the language of the contract, or the language of the additional insured endorsement in the policy. Identifying which additional insured endorsement is actually included in the named insured’s policy and what you must show to qualify as an additional insured depends entirely on its wording.
One of the most common additional insured endorsement forms in construction liability policies is “CG 20 10”, shown below:
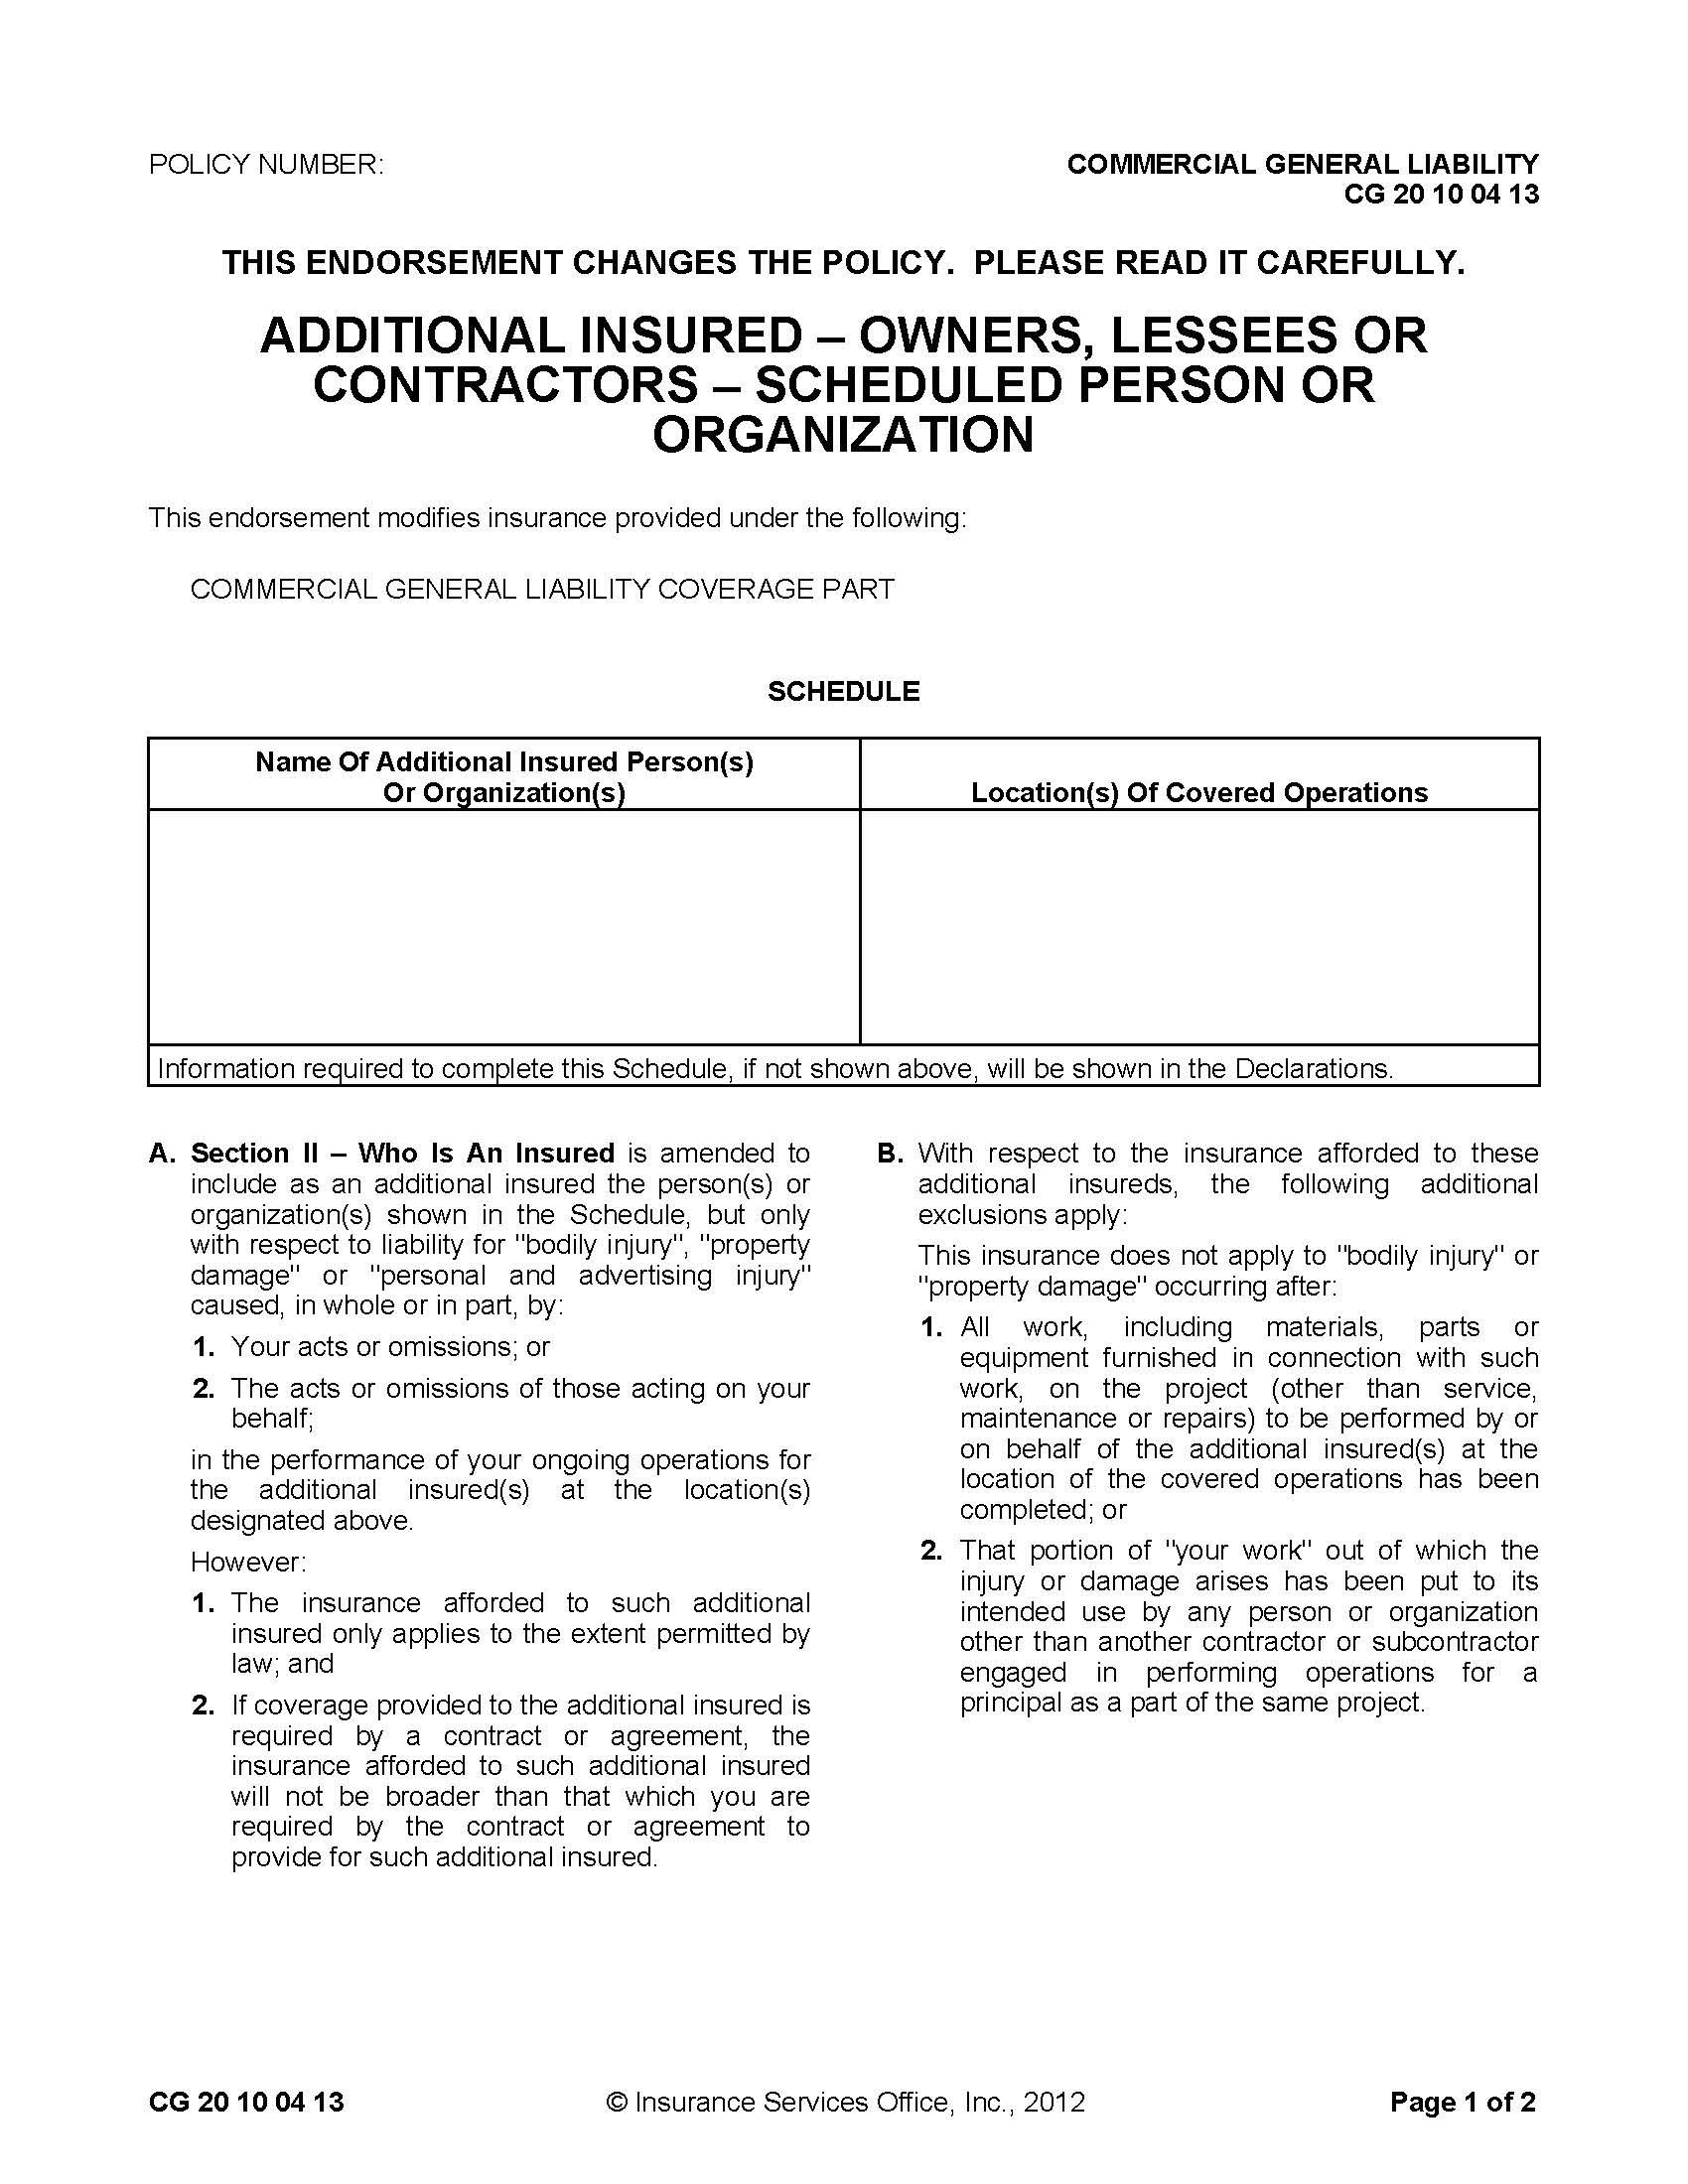
As seen above, under this endorsement4, a party will qualify as an additional insured if they are listed in the schedule. Often the schedule will identify the party directly. However, the schedule may also state – “as required by contract” or “as required by written contract with the insured.” If the party satisfies being identified in the schedule, then they will qualify as additional insured and be entitled to coverage for any claim that was “caused by, in whole or in part”, the “acts or omissions” of the named insured or the acts and omissions of those working on the named insured’s behalf. All these elements are discussed below.
Key takeaway: If you are the party requiring this coverage from a subcontractor or vendor, don’t leave the choice of form to the subcontractor’s broker. Specify the actual endorsement (e.g., CG 20 10, current edition) in the subcontract and require it to cover both ongoing and completed operations — not just the active construction period. That matters most for a property owner who may face a claim well after the project is finished.
Analyzing the Schedule
The Schedule used in the additional insured endorsement usually lists one of a few options.
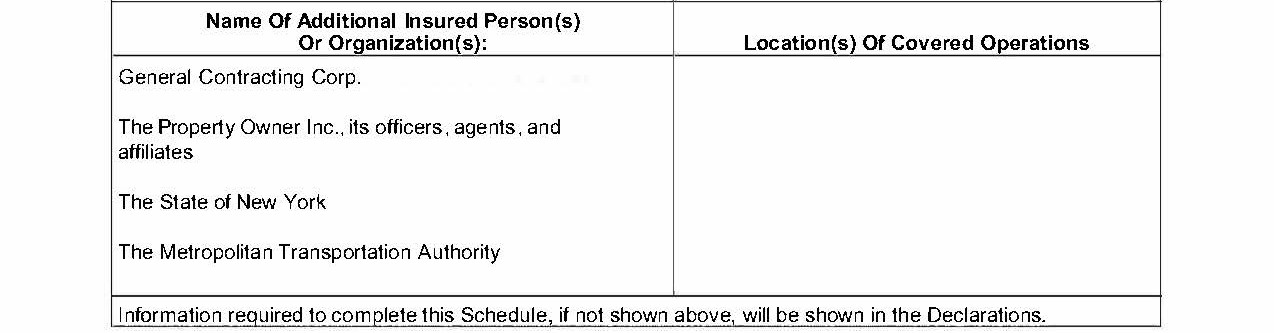
1. Scheduled Basis — the additional insured is specifically listed on the endorsement itself or on the declarations page. Four examples below:
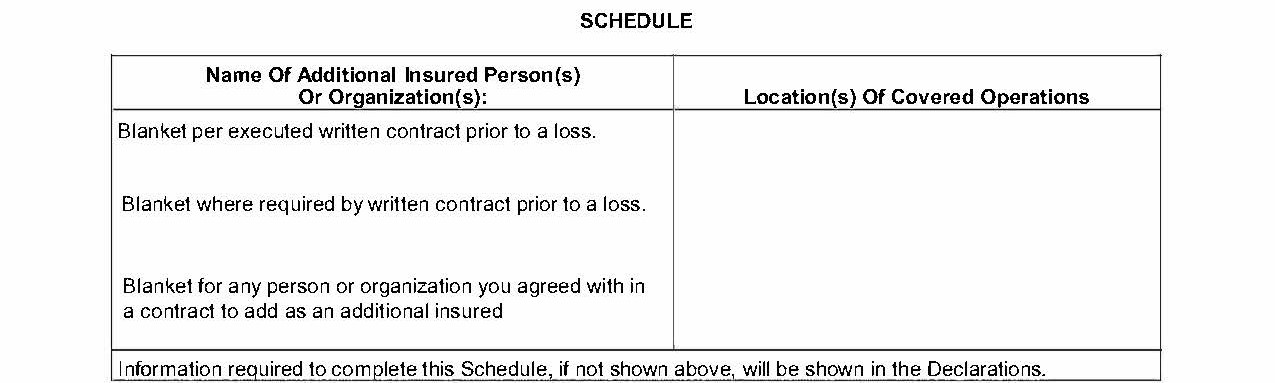
2. Automatic/Blanket Basis — additional insured status arises automatically whenever it is required by an outside agreement with the named insured. Three examples:
Does the Party Seeking Coverage Fall Within the Schedule?
If a party’s status depends on an outside agreement with the named insured (e.g., where required by contract), then the underlying agreement must satisfy the level of formality the schedule requires.
New York courts draw sharp distinctions between the terms “contract,” a “written contract,” and an “executed written contract.”5 Misjudging which tier applies is a common and avoidable reason that a tender fails.
(a) Satisfying an “agreement” or “contract”
At the base level, when the endorsement only requires there to be a “contract” or “agreement” requiring additional insured coverage, there need only be a binding contract requiring the named insured to procure additional insured coverage, in place on the date of loss. Some examples of what satisfies this term are as follows:
• A vendor’s profile on a commercial contractor directory, or a client’s vendor bulletin stating the client is typically listed as an additional insured, is not itself an agreement or contract to do so.6
• A proposal, estimate, or letter of intent (“LOI”) can qualify if the named insured and the other party showed intent to be bound — for example, by starting work — even if a more detailed agreement was meant to follow.7
• If a document is merely an “agreement to agree,” there is no agreement, as these documents typically include an express reservation that neither party is bound until a more formal agreement is signed.8
• A certificate of insurance listing you as an additional insured is not, itself, an agreement to procure that coverage.9
Key takeaway: If your agreement is informal or unsigned, look for conduct showing both sides treated themselves as bound — the sub mobilized on site, submitted invoices referencing the agreement, or was paid under it. That conduct can be enough on its own. If instead you are the one requiring this coverage from a sub, don’t build the program around a certificate of insurance: a COI is evidence of a policy, not proof of additional insured status, and is not itself an agreement to provide it. Always obtain and review the actual endorsement.
(b) Satisfying a “written contract”
The second tier of agreement requires that there be a “written contract”. Under New York law, a “written contract” must be in writing, but does not need to be signed.10
• An oral agreement or handshake will not satisfy “written contract,” even if memorialized in writing after the date of loss.11
• A certificate of insurance is not a “written contract” because it does not confer coverage.12
• A proposal or LOI (letter of intent) that qualifies as a contract at all will also satisfy “written contract.”13
• A purchase order with no signature lines can satisfy “written” — but not “signed” or “executed.”14
Key takeaway: Don’t assume you need a signature just because the endorsement says “written contract.” An unsigned but written proposal or purchase order can be enough at this tier — read the endorsement’s exact wording before assuming more is required.
(c) Satisfying an “executed written contract” or “signed written contract”
At this tier, executed means signed. If there is one signature line, this must be signed by the party seeking additional insured coverage. If there are two signature lines, both parties must sign. This is the tier where tenders often fail on a technicality.
• A proposal letter not signed by the construction manager seeking additional insured status did not satisfy “executed written contract.”15
• A contract with two signature lines but only one signature is not “executed.”16
• A purchase order with no signature lines cannot be a “signed/executed written contract.”17
Key takeaway: If the endorsement requires an executed or signed written contract, get the fully signed contract into the file before there’s a loss, as an unsigned proposal or a one-sided signature block will not be cured later, no matter how clear everyone’s intent was. If you are the one drafting the subcontract, build this in from the start: require the subcontract to be fully signed by both parties before the sub begins work on site, and don’t let work start on a proposal or purchase order alone if the endorsement you’re relying on requires an executed contract.
Other Contract Considerations – “Privity of Contract”
(a) Is “Privity of Contract” needed?
Example: a property owner hires a general contractor for roofing work (the “contract”). The general contractor then hires a subcontractor (the “subcontract”). The contract requires the general contractor to provide additional insured coverage to the property owner, and that the general contractor must require any subcontractor to name the owner as an additional insured. The subcontract requires the subcontractor to provide additional insured coverage for both the general contractor and the property owner. The property owner is not a party to the subcontract.
Under Form CG 20 10 (above), based on qualifying under a satisfying “written agreement”, both the general contractor and the owner are entitled to coverage under the subcontractor’s insurance. 18
Under Form CG 20 33, a stricter endorsement, only the general contractor would be entitled to coverage. The owner is not, because this endorsement requires direct privity of contract between the subcontractor and the party seeking additional insured coverage, which does not include the owner.19
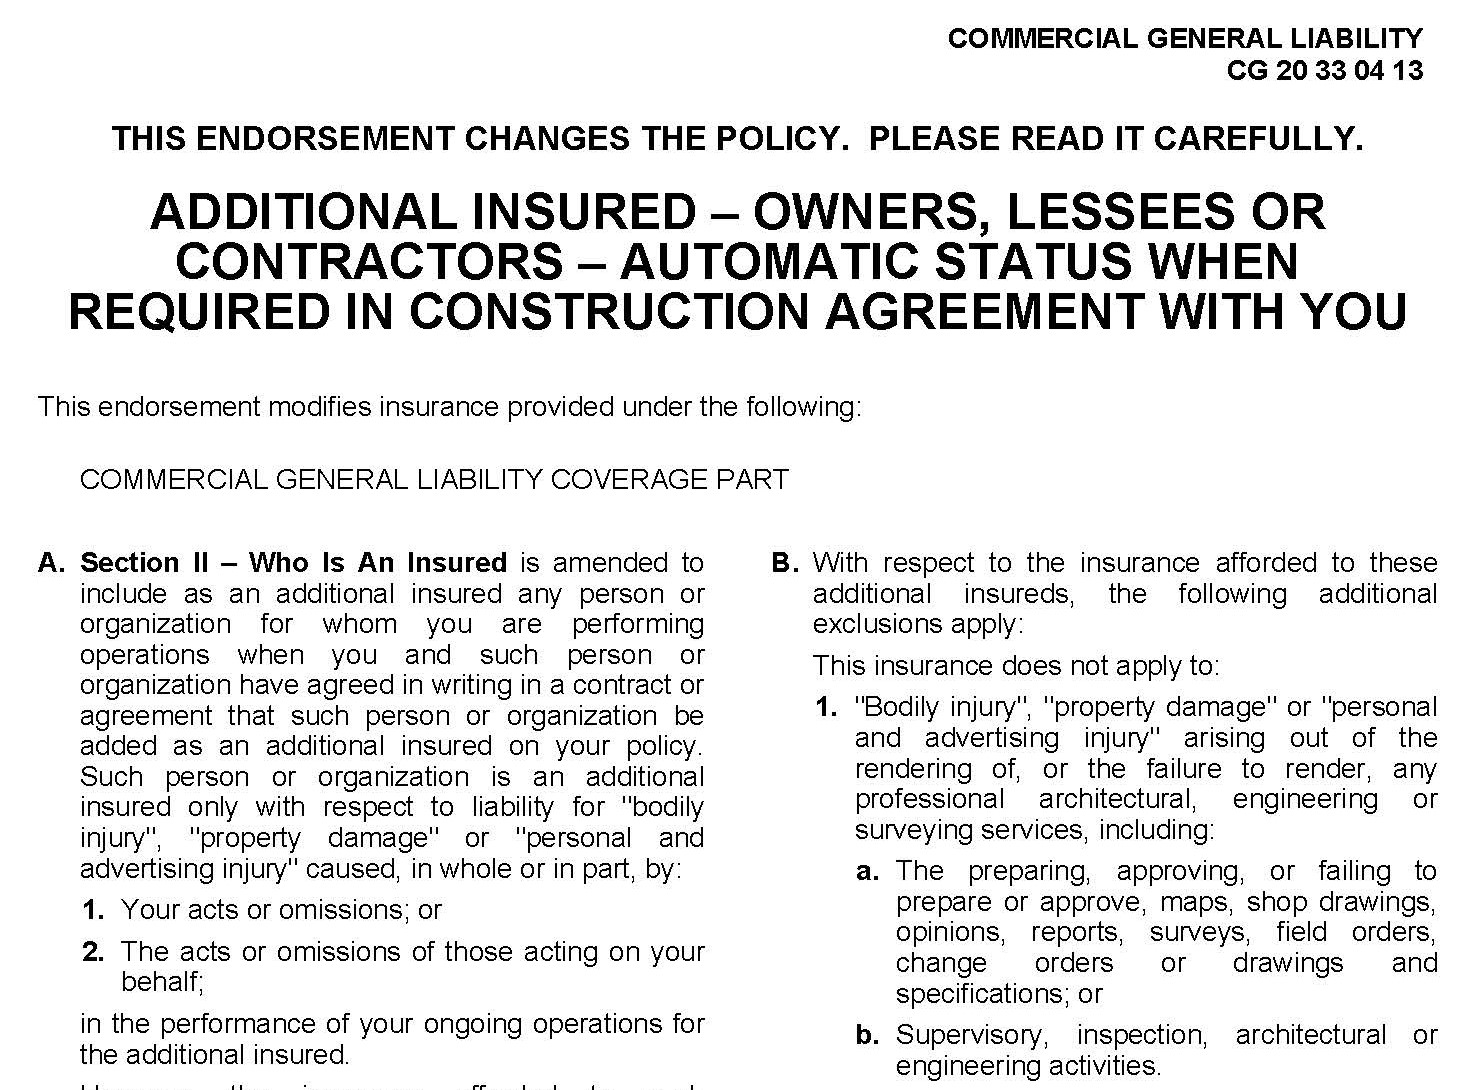
New York courts have held that if the policy contains a CG 20 33-type endorsement and the party seeking additional insured status has no written agreement directly with the purchaser of the insurance, there is no coverage, even if some other agreement provides that the supposed additional insured will receive it.20 This is because the endorsement states that additional insured status is only provided when there is a written contract “with you”, and “you” being the named insured. Because, in the above example, the owner does not have a written contract “with you” (i.e., the subcontractor), it does not qualify as an additional insured.
Key takeaway: If you are an owner or upper-tier contractor without a direct agreement with the sub whose policy you’re tendering to, this is the gap insurers commonly exploit. At the drafting stage, require CG 20 10 or an equivalent form that does not condition coverage on privity, or get a direct written agreement with the sub. Do not rely on a CG 20 33-type form in a multi-tier structure where you have no direct contract with the subcontractors or other downstream parties. If the loss has already happened and your contract with the sub only ties to CG 20 33, look for any direct writing, even an informal one, between you and the subcontractor before conceding the point.
Contract Issues: Does the contract require additional insured coverage?
Generally, the provision requiring the named insured to procure coverage for you in the underlying contract must be express and specifically stated.21 These following cases show how easily a generic insurance clause can fail to do the job:
(1) No coverage, where a contract requiring the named insured to purchase several forms of insurance for itself, without expressly requiring it to name the owner as an additional insured on its general liability coverage, does not create additional insured coverage.22
(2) No coverage, where a hold-harmless agreement with no requirement to name the owner as an additional insured does not create coverage.23
(3) No coverage, where an agreement to obtain liability insurance in one’s own right and separately hold the other party harmless does not create coverage.24
(4) No coverage, where a requirement of “general liability insurance” with “certificates to follow” only requires the named insured to hold its own coverage and provide proof of it — it does not create additional insured status.25
(5) No coverage, where a certificate of insurance listing the parties as additional insureds, standing alone, does not create coverage.26
(6) No coverage, where a general clause incorporating the insurance provisions of a prime contract by reference did not create coverage here — though this can be enough if the prime contract itself has specific, on-point terms for the subcontractor.27
(7) No coverage, where a blanket agreement requiring coverage for “specified owners” did not cover an owner who was not actually specified, even though it owned the property.28
(8) No coverage, where a requirement that the named insured provide certificates of insurance from its subs listing the owner as an additional insured, without more, was not enough.29
(9) No coverage, where a clause making insurance procurement a condition of an owner’s right to withhold payment — rather than an independent, express obligation — did not create coverage.30
(10) Coverage found, where a contract requiring a “certificate of insurance clearly setting forth the coverage for the equipment and naming [the party] as loss payee and additional insured” was specific enough.31
Key takeaway: Every “no coverage” result above traces back to a contract clause that was vague, generic, or conditional. When you are reviewing an existing contract before a loss or drafting the next one, insist on language that expressly says the contractor/subcontractor “shall name [Owner/GC] as an additional insured” under a specific CGL form, on a primary and noncontributory basis. General language just requiring “insurance” will not suffice. A clause incorporating “the insurance requirements of the prime contract” by reference can work, but only if the referenced document actually contains specific, on-point additional insured language for that subcontractor; don’t assume a passing reference is enough.
Identity of party issues — misnamed parties on the contract, policy, or schedule
New York is generally forgiving of naming errors, and courts have held that effectively naming the insured or additional insured is enough. The policy, schedule, or contract does not need to be 100% accurate, so long as it is clearly the same party. The following cases illustrate insurers trying to deny tenders over a technical misnomer, without success:
(1) An insurer could not withhold coverage over an error listing “Court Tobacco Co.” rather than “Court Tobacco Stores, Inc.”32
(2) A policy naming the “New York State Department of Social Welfare Commission for the Blind” was equivalent to naming the State of New York.33
(3) No meaningful difference between “Stoncor Group” and its trade name “Stonhard Corp.”34
(4) A subcontract requiring coverage for “Stellar Mechanical Services of N.Y. II” satisfied the requirement for “Stellar Mech. Services of New York, Inc.”35
(5) An insurer could not withhold coverage over a misidentified named insured where the intent to cover the project’s risk was clear.36
(6) An insurer’s obligation to cover a mortgage holder’s risk applied even though the mortgage holder was misidentified in the contract.37
(7) Even though only the former landlord was listed as the additional insured, the current landlord was entitled to coverage where the named insured had agreed to insure the landlord and the policy expressly covered the landlord’s risk.38
Key takeaway: If you are the one drafting the subcontract, get entity names right — but don’t panic over minor variations that do slip through. New York courts will look past immaterial misnomers so long as the intended party is clear, as the cases above show.
Once you have established that you qualify as an additional insured, the analysis turns to whether the insurer’s duty to defend, and ultimately its duty to indemnify, has been triggered. Those issues, along with the policy conditions and exclusions that can stop coverage for an event and the requirements Insurance Law § 3420(d) imposes on an insurer when it responds to a tender or denies coverage, are addressed in Part 2 of this article.
If you are drafting or negotiating a contract with a contractor, subcontractor, or any downstream party, build these protections into the contract before the work or contract begins:
• Express, specific language that the subcontractor “shall name [Owner/GC] as an additional insured”, on a primary and noncontributory basis, with specific limits. Make sure not to only use generic language requiring only that the sub “maintain insurance”;
• A fully executed contract, signed by both parties before work begins;
• State the specific additional insured endorsement form (e.g., CG 20 10), covering both ongoing and completed operations; and
• Ensure that additional downstream entities do not require direct privity-of-contract, such as in a CG 20 33-type endorsement.
* * *
Aboulafia Law Firm LLC works exclusively on behalf of policyholders and has decades of experience fighting insurance companies. Whether you are dealing with a residential or commercial property claim, we are ready to help you. If you are seeking to obtain additional insured coverage or are dealing with a tender, don’t navigate the complex claims process alone. For assistance on your insurance claim, please contact us.
The opinions expressed are those of the author(s) and do not necessarily reflect the views of the firm, its clients, or any of its or their respective affiliates. This article is for general information purposes and is not intended to be and should not be taken as legal advice.
Aaron Jacob is a senior associate at Aboulafia Law Firm LLC. Mr. Jacob is a skilled litigation and coverage attorney and has extensive experience representing commercial and private clients involved in property damage and insurance coverage claims in complex state and federal court matters.
Mr. Jacob focuses his practice on advocating for policyholders in high-exposure property damage cases, insurance recovery claims, coverage disputes, construction-related claims, declaratory judgments, first & third-party claims, business interruption losses, indemnification, additional insured coverage, broker negligence, risk transfer, contractor/subcontractor liability, bad faith claims, contribution claims, breach of contract disputes, and general liability defense, as well as in litigating insurance coverage issues under several policy lines including homeowners, commercial liability, excess/umbrella, businessowners, cargo, freighting, and commercial auto policies.
Footnotes
1. Pecker Iron Works of N. Am., Inc. v. Travelers Ins. Co., 99 N.Y.2d 391 (2003). ↩
2. Id., see also BP Air Conditioning Corp. v. One Beacon Ins. Grp., 8 N.Y.3d 708, 715 (2007). ↩
3. Tribeca Broadway Associates, LLC v. Mt. Vernon Fire Ins. Co., 774 N.Y.S.2d 11, 13 (1st Dept. 2004). ↩
4. This specific endorsement form is usually the most lenient and advantageous for additional insureds. ↩
5. Chipotle Mexican Grill, Inc. v. RLI Ins. Co., 158 N.Y.S.3d 201, 205 (2nd Dept. 2021) (“agreement” or “contract”); Zurich Am. Ins. Co. v. Endurance Am. Speciality Ins. Co., 43 N.Y.S.3d 40, 41 (1st Dept. 2016) (“written contract”); Nicotra Group, LLC v. Am. Safety Indem. Co., 850 N.Y.S.2d 455, 457 (1st Dept. 2008) (“executed written contract”). ↩
6. Chipotle Mexican Grill, Inc. v. RLI Ins. Co., 158 N.Y.S.3d 201, 205 (2nd Dept. 2021). ↩
7. Bed Bath & Beyond Inc. v. IBEX Const., LLC, 860 N.Y.S.2d 107, 109 (1st Dept. 2008); Netherlands Ins. Co. v. Endurance Am. Specialty Ins. Co., 66 N.Y.S.3d 441, 442 (1st Dept. 2018). ↩
8. Emigrant Bank v. UBS Real Est. Securities, Inc., 854 N.Y.S.2d 39, 41 (1st Dept. 2008). ↩
9. Chipotle, 158 N.Y.S.3d at 205. ↩
10. Zurich Am. Ins. Co. v. Endurance Am. Speciality Ins. Co., 43 N.Y.S.3d 40, 41 (1st Dept. 2016). ↩
11. Landsman Dev. Corp. v. RLI Ins. Co., 53 N.Y.S.3d 428, 430 (4th Dept. 2017). ↩
12. ALIB, Inc. v. A. Cas. Ins. Co., 861 N.Y.S.2d 28, 29 (1st Dept. 2008). ↩
13. Bed Bath & Beyond, 860 N.Y.S.2d at 108–09. ↩
14. Zurich Am. Ins. Co., 43 N.Y.S.3d at 41. ↩
15. Nicotra Group, LLC v. Am. Safety Indem. Co., 850 N.Y.S.2d 455, 457 (1st Dept. 2008); Natl. Abatement Corp. v. Natl. Union Fire Ins. Co. of Pittsburgh, PA, 824 N.Y.S.2d 230, 232 (1st Dept. 2006). ↩
16. Cusumano v. Extell Rock, LLC, 86 A.D.3d 448, 449, 927 N.Y.S.2d 627 (1st Dept. 2011). ↩
17. Zurich Am. Ins. Co., 43 N.Y.S.3d at 41. ↩
18. Direct privity of contract can also be required under Form CG 20 10, depending on the language used in the schedule. E.g., if the schedule purports to only provide coverage for people that “you agreed with” in a contract, some courts may interpret that language as requiring direct privity of contract. Under this language, the analysis is comparable to CG 20 33. ↩
19. See, above. ↩
20. See Gilbane Bldg. Co./TDX Constr. Corp. v St. Paul Fire & Mar. Ins. Co., 143 AD3d 146, 152, 38 NYS3d 1 [1st Dept 2016], aff’d 31 NY3d 131, 74 NYS3d 162, 97 NE3d 711 [2018]; AB Green Gansevoort, LLC v Peter Scalamandre & Sons, Inc., 102 AD3d 425, 426–427, 961 NYS2d 3 [1st Dept 2013]. ↩
21. Trapani v. 10 Arial Way Associates, 755 N.Y.S.2d 396, 398 (2nd Dept. 2003). ↩
22. 140 Broadway Prop. v. Schindler Elevator Co., 901 N.Y.S.2d 292, 293 (2d Dept. 2010). ↩
23. Hargob Realty Associates, Inc. v. Fireman’s Fund Ins. Co., 901 N.Y.S.2d 657, 659 (2nd Dept. 2010). ↩
24. Mangano v. Am. Stock Exch., Inc., 651 N.Y.S.2d 494, 495 (1st Dept. 1996). ↩
25. Trapani v. 10 Arial Way Associates, 755 N.Y.S.2d 396 (2nd Dept. 2003). ↩
26. Chipotle, 158 N.Y.S.3d at 205. ↩
27. Lexington Ins. Co. v. Kiska Dev. Group LLC, 122 N.Y.S.3d 590, 592 (1st Dept. 2020). ↩
28. 77 Water St., Inc. v. JTC Painting & Decorating Corp., 50 N.Y.S.3d 471, 475 (2nd Dept. 2017). ↩
29. Ramcharan v. Beach 20th Realty, LLC, 942 N.Y.S.2d 593, 597 (2nd Dept. 2012). ↩
30. Lexington Ins. Co. v. Kiska Dev. Group LLC, 122 N.Y.S.3d 590, 592 (1st Dept. 2020). ↩
31. United Rentals (N.A.), Inc. v. Conti Enterprises, Inc., 293 F. Supp. 3d 447, 456 (S.D.N.Y. 2018) (applying NY law). ↩
32. Court Tobacco Stores, Inc. v. Great Eastern Insurance Company, 43 A.D.2d 561 (3rd Dept. 1973). ↩
33. State v. Ins. Co. of N.A., 333 N.Y.S.2d 486 (3d Dept. 1972). ↩
34. Stoncor Group, Inc. v. Peerless Ins. Co., 322 F. Supp. 3d 505, 508 (S.D.N.Y. 2018). ↩
35. Stellar Mech. Services of New York, Inc. v. Merchants Ins. of New Hampshire, 903 N.Y.S.2d 471, 475 (2d Dept. 2010). ↩
36. N.Y. Cas. Ins. Co. v. Shaker Pine, 262 A.D.2d 735, 736 (3rd Dept. 1999). ↩
37. Cheperuk v. Liberty Mutual Fire Insurance Company, 263 A.D.2d 748 (3d Dept. 1999). ↩
38. 137 Broadway Associates, LLC v. 602 W. 137th Deli Corp., 975 N.Y.S.2d 710 (N.Y. Sup. Ct. 2013). ↩
